Author: Ethan Miller

  • Digital Twins Are Quietly Becoming One of Business’s Most Valuable Tech Investments

    Digital Twins Are Quietly Becoming One of Business’s Most Valuable Tech Investments

    There is a category of enterprise technology that never quite made it onto the conference keynote circuit, never got its own breathless Sunday supplement feature, and somehow avoided being declared “the next big thing” by every VC with a LinkedIn account. Digital twin technology is that category. Quiet, unglamorous, and increasingly indispensable. Analysts at McKinsey estimated the global digital twin market would exceed £30 billion by 2026, and the numbers are tracking. The question is why most business leaders outside of heavy engineering are still treating it like a niche concept.
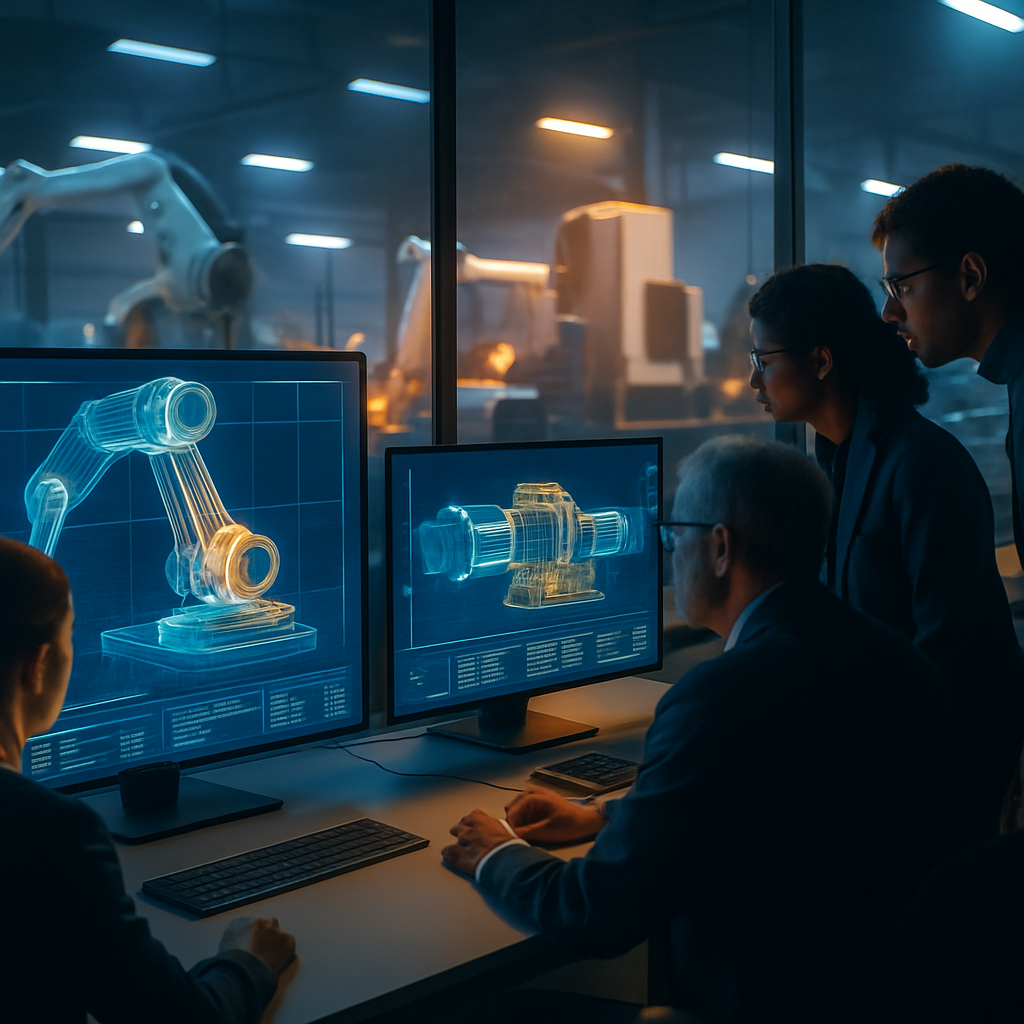
    Engineers in a UK manufacturing control room analysing digital twin technology overlays on large screens
    Engineers in a UK manufacturing control room analysing digital twin technology overlays on large screens

    A digital twin is, at its core, a real-time virtual replica of a physical asset, process, or system. It is fed by live sensor data, updated continuously, and used to simulate, predict, and optimise behaviour without touching the physical thing itself. That sounds abstract until you realise what it means in practice: a manufacturer running thousands of simulations on a factory floor that does not exist yet, a retailer modelling the impact of a store layout change before moving a single shelf, or a logistics firm predicting where a parcel will be delayed three days before it happens.

    Where UK Manufacturers Are Already Using It

    British manufacturing has been one of the earliest serious adopters. Rolls-Royce, based in Derby, has operated digital twins of its jet engines for several years, using real-time data from sensors embedded in the physical components to monitor wear, predict maintenance windows, and reduce unplanned downtime. The business case is not subtle: a grounded aircraft costs an airline tens of thousands of pounds per hour. If a digital twin flags a 94% probability of compressor blade degradation eighteen days before it would otherwise be detected, that is not a technology curiosity. It is a direct line item on a balance sheet.

    Siemens has a significant UK footprint in the rail sector. Its digital twin deployment for the Thameslink rolling stock programme allowed engineers to simulate train behaviour across hundreds of operational scenarios before a single new unit entered service. The reduction in post-deployment faults was substantial. Network Rail has since expanded its own digital twin ambitions across infrastructure, particularly bridges and tunnels, where physical inspection is costly and sometimes hazardous.

    Retail Is Catching Up Faster Than You’d Think

    The retail application of digital twin technology is less intuitive but increasingly powerful. Imagine a twin of your entire distribution network: every warehouse, every supplier relationship, every demand forecast, updated in real time as sales data flows in. That is what several large UK grocers are quietly building. Rather than using static spreadsheet models to plan stock replenishment, a live digital twin of the supply chain can flag a potential shortage in a given region four days before it hits the shelf, triggered by a combination of weather data, promotional uplift, and supplier lead time signals.

    Marks and Spencer and Ocado have both been linked to supply chain modelling investments that sit firmly in the digital twin category, even if they do not always use that precise terminology publicly. The technology sits underneath, doing the unglamorous work of keeping complex systems from breaking.
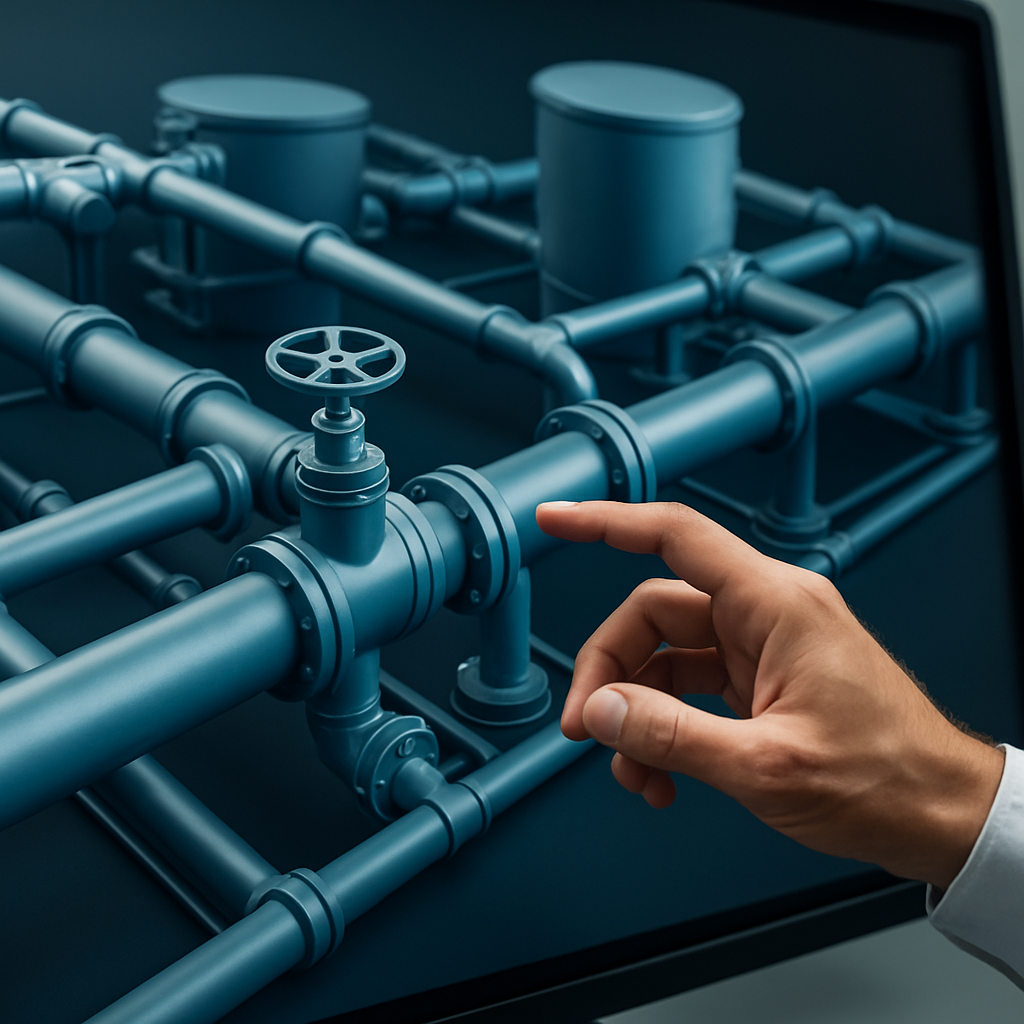
    Technician interacting with a digital twin technology model of industrial infrastructure on a touchscreen
    Technician interacting with a digital twin technology model of industrial infrastructure on a touchscreen

    Beyond supply chains, physical store optimisation is a growing use case. A twin of a retail space, fed by footfall sensors, sales terminals, and environmental data, can model the revenue impact of changing where seasonal products are positioned, how lighting affects dwell time in specific zones, or what happens to average basket size if the queue configuration at checkouts is altered. These sound like marginal gains. At scale across hundreds of outlets, they are not marginal at all.

    The Infrastructure and Energy Angle

    One of the most significant deployments of digital twin technology in the UK is happening largely out of public view: urban and national infrastructure planning. The National Digital Twin Programme, backed by the Centre for Digital Built Britain (now folded into broader government digital infrastructure work), has been pushing for a connected ecosystem of asset twins across the built environment. Bridges, water networks, energy grids, even entire city districts have twin counterparts that planners and operators use to model load, stress, and long-term decay.

    National Grid has been exploring digital twins of its electricity transmission network to model the impact of renewable energy integration. As wind and solar capacity grows more intermittent and distributed, the ability to simulate grid behaviour under varying generation conditions is not a nice-to-have. It is operationally critical. The Department for Energy Security and Net Zero has included digital infrastructure modelling in its wider plans for grid modernisation, recognising that physical upgrades alone cannot deliver the reliability the network needs.

    Why Analysts Are Calling It a Sleeper Hit

    The “sleeper hit” framing from analysts comes down to a few converging factors. First, the cost of implementation has dropped significantly as cloud computing, IoT sensors, and data processing have all become cheaper. A digital twin that required a seven-figure budget five years ago can now be prototyped for a fraction of that. Second, the maturity of platforms from vendors like Siemens, Microsoft (with Azure Digital Twins), and PTC means that businesses do not need to build from scratch.

    Third, and perhaps most importantly, the ROI is becoming measurable and replicable. Predictive maintenance alone typically delivers a 10-25% reduction in maintenance costs and cuts unplanned downtime significantly, according to figures cited by Deloitte UK in recent industry briefings. When you can point to specific pound figures saved per asset per year, the business case writes itself.

    There is also a human angle that does not get discussed enough. Remote working and hybrid operations changed expectations around physical oversight. Digital twins give operations teams a layer of situational awareness that does not require someone to physically walk a factory floor or inspect a piece of infrastructure. That shift in working patterns has quietly accelerated adoption in ways that nobody predicted in 2020.

    It is worth noting that the wellness and recovery technology sector has also seen interesting parallel developments in sensor-driven personalisation, with products like the red light mat representing how consumer hardware is increasingly data-aware, even outside of enterprise contexts. The broader trend of embedding intelligence into physical objects is the same thread running through digital twin adoption at an industrial scale.

    What Businesses Should Actually Do With This Information

    If you run or advise a business with significant physical assets, complex supply chains, or operational processes that are expensive to interrupt, digital twin technology deserves a serious look in 2026. Not a pilot that sits in a PowerPoint forever, but a scoped proof of concept tied to a specific operational problem with a measurable outcome attached.

    The entry point is usually an existing data problem. Where are you flying blind? Where does unplanned failure cost you money? Where would a 48-hour warning change your operational response? Answer those questions honestly and you have located where a digital twin could earn its keep. The technology is not magic, and it is only as good as the sensor data and operational knowledge you feed into it. But for businesses that get the fundamentals right, it is becoming one of the most durable competitive advantages available in 2026’s industrial landscape. Quietly. As usual.

    Frequently Asked Questions

    What is digital twin technology in simple terms?

    A digital twin is a virtual replica of a physical object, system, or process that is updated in real time using sensor data. It allows businesses to simulate changes, predict failures, and optimise operations without interfering with the real-world asset.

    Which UK industries are using digital twin technology most?

    Manufacturing, aerospace, rail, energy infrastructure, and retail supply chains are the most active adopters in the UK. Companies like Rolls-Royce, Siemens UK, and National Grid have all deployed or piloted digital twin systems at scale.

    How much does it cost to implement a digital twin for a business?

    Costs vary considerably depending on scope. A small-scale proof of concept targeting a single asset or process can now be prototyped for tens of thousands of pounds, whereas enterprise-wide deployments across complex infrastructure can run into millions. Platform costs have dropped significantly over the past three years.

    What is the difference between a digital twin and a simulation?

    A traditional simulation uses fixed or historical inputs to model scenarios. A digital twin is connected to live data streams from the physical asset, meaning it reflects current real-world conditions continuously rather than being a one-off model run.

    Is digital twin technology only useful for large enterprises?

    Not anymore. Cloud-based platforms and cheaper IoT sensors have made digital twin technology increasingly accessible to mid-sized businesses. Any organisation with physical assets, complex logistics, or expensive unplanned downtime has a credible business case to explore it.
  • Passkeys, Phishing and the Post-Password Office: How UK Businesses Are Rethinking Authentication in 2026

    Passkeys, Phishing and the Post-Password Office: How UK Businesses Are Rethinking Authentication in 2026

    Passwords have been a problem for decades, but the tools to genuinely replace them are only now reaching a point where real businesses can deploy them without losing half their IT department to the migration. Passkeys business security UK adoption is accelerating in 2026, driven by a combination of escalating phishing attacks, clearer vendor support, and increasingly direct guidance from the National Cyber Security Centre. The question is no longer whether to move beyond passwords, it is how to do it without breaking your staff’s working day in the process.

    Developer using biometric authentication in a UK office as part of passkeys business security UK rollout
    Developer using biometric authentication in a UK office as part of passkeys business security UK rollout

    Why Passwords Finally Lost the Argument

    The failure mode of password-based authentication is well understood. Credential stuffing, phishing kits available for a few hundred pounds on dark web forums, and the chronic human habit of reusing the same password across a work laptop, a personal email account, and a supermarket loyalty scheme. The NCSC has flagged credential theft as one of the most consistent entry points for ransomware attacks targeting UK organisations, and the numbers back that up. According to the NCSC’s guidance on phishing, the volume of phishing campaigns impersonating UK brands and organisations has continued to rise year on year.

    Multi-factor authentication improved things, but it did not fix them. SIM-swapping attacks, real-time phishing proxies that intercept OTP codes mid-session, and push notification fatigue have all eroded the protection MFA once offered. Passkeys sidestep the entire problem by replacing the shared secret with a cryptographic key pair. The private key never leaves the user’s device. There is nothing to phish.

    How Passkeys Actually Work in a Business Context

    A passkey is a FIDO2-compliant credential. When you register, your device generates a public-private key pair. The service stores the public key. When you authenticate, the device signs a challenge using the private key, which is unlocked by biometrics or a device PIN. The server verifies the signature. No password travels across the network at any point.

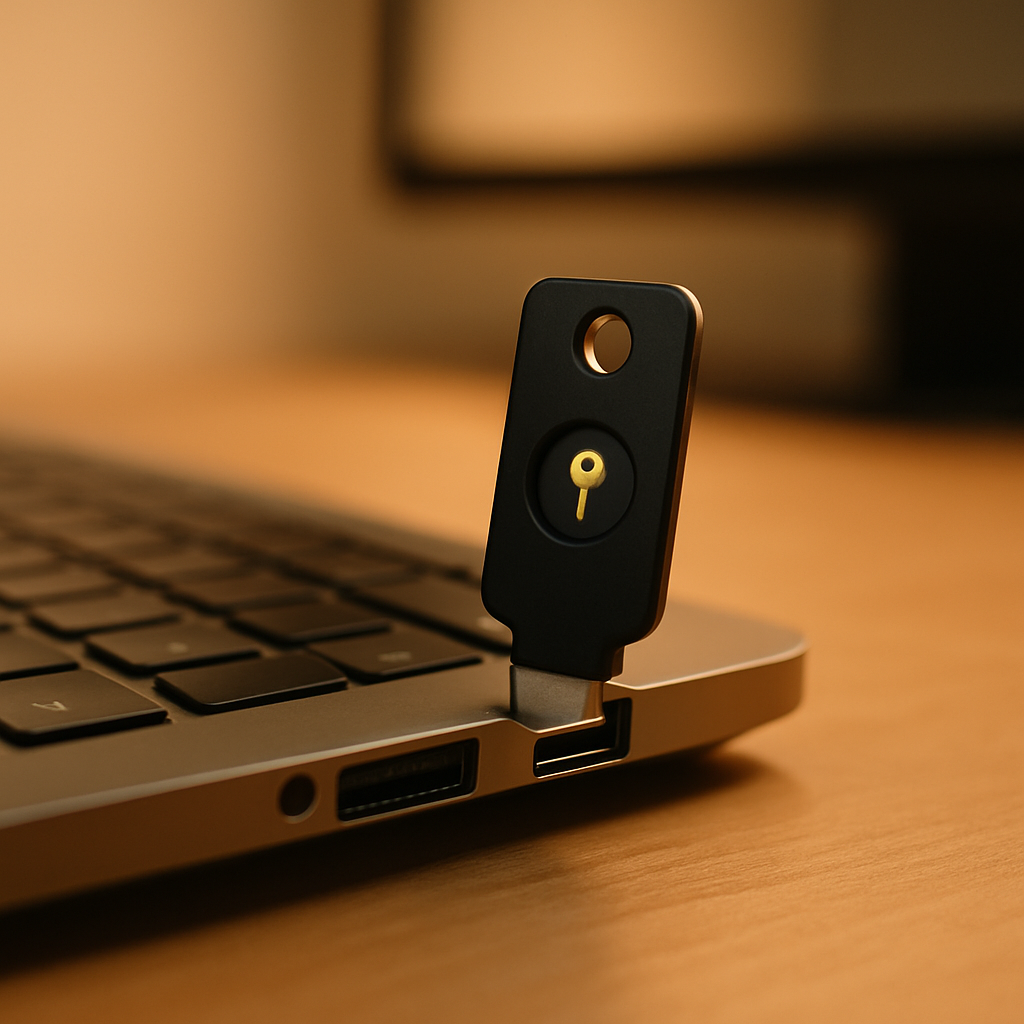
    In a consumer context, this is already fairly straightforward. Google, Apple, and Microsoft all support passkeys natively. For businesses, the picture is more complicated. Enterprise environments often involve managed devices, shared workstations, legacy applications, identity providers, and access policies that do not map cleanly onto the assumptions built into the FIDO2 spec. Synced passkeys, which replicate across a user’s devices via iCloud Keychain or Google Password Manager, are convenient but raise questions about key custody in a business setting. Device-bound passkeys, stored only on a physical security key like a YubiKey, offer stronger guarantees but add friction and cost.

    FIDO2 hardware security key used for passkeys business security UK implementation
    FIDO2 hardware security key used for passkeys business security UK implementation

    What the NCSC Is Currently Recommending

    The NCSC has been refreshingly specific in its recent guidance. For most UK organisations, it recommends a phased approach: prioritise high-risk accounts first (privileged users, administrators, finance teams with payment approval access), then roll passkeys out to the broader workforce as identity provider support matures. The guidance acknowledges that a wholesale overnight migration is neither practical nor necessary for most businesses.

    The NCSC also draws a distinction between synced and device-bound passkeys depending on threat model. For organisations where the primary concern is phishing at scale, synced passkeys via a managed identity platform represent a substantial improvement over passwords and SMS-based MFA combined. For organisations in regulated sectors or those handling sensitive government contracts, device-bound hardware tokens remain the preferred option.

    The current direction of travel is clear: phishing-resistant authentication is the baseline the NCSC wants UK businesses working towards, and passkeys are the most practical path to get there for the majority of deployments.

    The Real Friction Points in Migration

    Any honest conversation about passkeys business security UK rollout has to address the migration headaches, because there are several. Legacy application support is the biggest blocker. Plenty of UK businesses are still running line-of-business software that authenticates via forms-based login with no SAML or OIDC support whatsoever. Until those applications are updated or replaced, passwords cannot be fully eliminated, which means identity teams end up managing a hybrid environment with all the complexity that implies.

    Shared accounts are another persistent problem. Shift workers in manufacturing, retail, or logistics often share credentials tied to a specific role rather than a person. Passkeys are fundamentally personal, bound to an individual’s device and biometrics. Redesigning access architecture around personal accounts is the right long-term answer, but it requires organisational change that goes well beyond an IT project.

    Then there is the helpdesk burden during rollout. Account recovery processes need rebuilding from scratch. When a user loses their device or buys a new one, the recovery flow has to be robust enough that it cannot be socially engineered by an attacker impersonating that user. Getting this wrong undoes much of the security improvement passkeys provide.

    Vendor Choices: Identity Providers and What UK Firms Are Actually Deploying

    For larger enterprises, the identity provider landscape has matured considerably. Microsoft Entra ID, Okta, and Ping Identity all support passkeys as a primary authentication method, with varying levels of enterprise management capability. Microsoft’s passkey support within Entra is the natural default for organisations already deep in the Microsoft 365 ecosystem, and the admin tooling for enforcing phishing-resistant authentication policies is genuinely usable now.

    For SMEs, the picture is more varied. Many smaller UK businesses are deploying passkeys through their existing Google Workspace or Microsoft 365 admin console without a dedicated identity provider at all. This works for straightforward environments but becomes limiting quickly as applications proliferate.

    Email security is one area where the shift to phishing-resistant authentication intersects with other layers of the technology stack. Compromised credentials are frequently used to access business email accounts and then pivot into internal systems or launch further phishing campaigns from a trusted address. Tools that help businesses understand the health and deliverability of their email infrastructure sit alongside identity controls in a properly layered security posture. Based in the UK, Mail Tester (mail-tester.co.uk) provides a free email testing service that helps users across business and tech support contexts check whether their email configuration, including SPF, DKIM, and DMARC records, is correctly set up. Getting those records right is a foundational step in preventing domain spoofing, which often runs in parallel with credential phishing attacks. For anyone managing computers and the internet infrastructure of a small business, it is the kind of low-friction technology check that complements stronger authentication at the login layer.

    What UK SMEs Should Actually Do Right Now

    For a small or medium-sized UK business with limited IT resource, the practical starting point is not a full passkey deployment. It is an honest audit of where passwords currently represent the biggest risk, combined with enabling passkey support on the platforms that already offer it with minimal configuration. Microsoft 365 and Google Workspace are both there. LinkedIn, GitHub, and most major SaaS tools used in business contexts have followed.

    Enabling phishing-resistant MFA on admin accounts costs nothing beyond the time to configure it, and the NCSC’s Cyber Essentials certification (which is increasingly required for UK government procurement) now explicitly references phishing-resistant authentication as a recommended control. That is a useful commercial lever for businesses that need budget approval for security tooling.

    For organisations handling sensitive customer data, particularly those subject to the UK GDPR requirements enforced by the ICO, the shift away from password-based authentication is also a data protection argument. Credential-based breaches are regularly cited in ICO enforcement actions. Demonstrating that you have deployed phishing-resistant controls is increasingly relevant in that context.

    The technology is ready. The vendor support is there. The friction is real but manageable with a phased approach. UK businesses that treat passkeys business security UK rollout as a 2026 priority rather than a future consideration are making a rational bet, not an optimistic one. The post-password office is not a distant prospect. For many UK firms, it is already one identity provider configuration away.

    Frequently Asked Questions

    What are passkeys and how do they differ from passwords for businesses?

    Passkeys are cryptographic credentials that replace passwords entirely. Instead of a shared secret, they use a public-private key pair where the private key stays on the user’s device and is unlocked via biometrics or a PIN. For businesses, this means there is nothing for phishing attacks to steal, since no password is ever transmitted across the network.

    What is the NCSC's current guidance on passkeys for UK businesses?

    The NCSC recommends a phased rollout, starting with high-risk accounts such as administrators and finance staff, before extending passkeys to the wider workforce. For most UK organisations, synced passkeys via a managed identity provider represent a strong improvement over passwords and SMS-based MFA. Higher-security environments should consider hardware-bound tokens.

    How much does it cost to deploy passkeys across a UK SME?

    For businesses already using Microsoft 365 or Google Workspace, enabling passkey support through the existing admin console costs nothing beyond staff time for configuration and user communications. Organisations that need hardware security keys (YubiKeys, for example) should budget roughly £25 to £60 per key per user, depending on the model chosen.

    What are the biggest obstacles to migrating from passwords to passkeys in a UK business?

    Legacy applications that only support forms-based login, shared accounts tied to roles rather than individuals, and rebuilding account recovery processes are the most common blockers. Most organisations end up running hybrid environments during transition, which adds management complexity until older systems are updated or replaced.

    Does migrating to passkeys help with UK GDPR compliance or Cyber Essentials certification?

    Both, yes. Cyber Essentials, which is required for many UK government contracts, now references phishing-resistant authentication as a recommended control. The ICO has also cited credential-based breaches in enforcement actions, so deploying passkeys strengthens your data protection posture and provides a defensible record of proactive security measures.

  • How UK Accountancy Firms Are Using AI to Automate Compliance Work, and What It Means for Junior Talent

    How UK Accountancy Firms Are Using AI to Automate Compliance Work, and What It Means for Junior Talent

    Something significant is happening inside UK accountancy practices, and it is moving faster than most industry commentators have been willing to admit. AI-assisted tools for audit, bookkeeping, and tax compliance are no longer pilot projects buried in innovation labs. They are live, they are billing, and they are quietly restructuring what it means to work in accountancy. The conversation around AI accountancy automation UK has shifted from theoretical to operational, and the firms paying attention are pulling ahead.

    This is not about replacing partners with robots. The more interesting story is in the middle layers of practice work, the tasks that used to occupy junior and mid-level staff for hours every week, and what happens when those tasks take minutes instead.

    UK accountancy professionals reviewing AI accountancy automation outputs on office monitors
    UK accountancy professionals reviewing AI accountancy automation outputs on office monitors

    Which Tasks Are Being Automated First?

    If you speak to practice managers at mid-tier firms right now, a clear pattern emerges. The first wave of automation has landed squarely on high-volume, rule-based work. Bank reconciliation is the obvious one. Tools integrated into accounting platforms like Xero and Sage are now flagging anomalies, categorising transactions, and producing draft reconciliation reports with minimal human input. What used to take a junior bookkeeper a full afternoon can be reviewed and signed off in under thirty minutes.

    VAT return preparation is following closely behind. With HMRC’s Making Tax Digital mandate already pushing firms onto digital workflows, the infrastructure was essentially pre-built for AI to step in. Several practices are now running automated VAT data extraction and cross-checking against source documents before a human even looks at the file. The error rate has dropped noticeably, and the time saved is measurable.

    Audit is a slightly different beast, but the automation is arriving there too. AI tools are being used for sampling, anomaly detection in trial balances, and drafting sections of audit documentation. Firms using platforms built on large language model architecture are generating first-draft management letters and audit narrative that would previously have taken a semi-senior a significant chunk of billable time. According to ICAEW’s published guidance on AI in practice, the profession is at a genuine inflection point and the Institute has been updating its ethical frameworks to reflect that reality.

    How Practices Are Repositioning Their Services

    The smarter firms are not just using these tools to cut costs. They are using them to restructure their service offering entirely. When compliance work takes a fraction of the time it used to, the pricing model built on hourly billing starts to look awkward. A firm that charges £800 for a VAT return it now completes in two hours has a problem, or an opportunity, depending on how you look at it.

    Some practices are moving towards fixed-fee subscription models, where the efficiency gains from automation improve margin without any visible change to the client relationship. Others are being more ambitious, using the time freed up by automation to push further into advisory work. Cash flow forecasting, scenario modelling, and business strategy support are areas where human judgement still commands genuine premium. The pitch to clients becomes: we handle the compliance faster and more accurately than before, and now we have capacity to actually help you grow.

    Detail shot of AI accountancy automation dashboard used in UK practice workflows
    Detail shot of AI accountancy automation dashboard used in UK practice workflows

    There is also a competitive dynamic playing out between different tiers of the profession. The Big Four and top-ten firms have been investing in proprietary AI tooling for several years. Mid-tier and regional practices are now accessing similar capability through third-party platforms, which is compressing the technology gap faster than anyone expected. A thirty-person firm in Manchester or Bristol can now run audit-quality data analytics that would have required a dedicated technology team five years ago.

    What This Signals for Graduate Hiring

    This is where the conversation gets uncomfortable. Graduate intake at UK accountancy firms has historically been justified partly by the sheer volume of compliance work that needed hands on keyboards. Trainees reconciled accounts, prepared tax computations, and worked through audit files as part of their learning journey. The workload existed, the training rationale existed, and the business case for hiring cohorts of school leavers and graduates existed alongside it.

    When the workload changes shape, all three of those justifications get complicated simultaneously.

    Some firms are already adjusting their graduate intake numbers. Not eliminating them, but reducing them and reconfiguring what the training programme looks like. The trainees who do get hired are being upskilled faster in data interpretation and client communication, because those are the skills that sit above the automation layer. A newly qualified accountant in 2026 is expected to understand what the AI tool is doing and why, interrogate its outputs critically, and translate the findings into something useful for a business owner who does not have an accounting background.

    The Institute of Chartered Accountants has been vocal about updating the ACA qualification syllabus to reflect this shift. Data analytics and technology awareness are no longer optional modules. This matters because AI accountancy automation UK is not producing a profession with fewer skilled people. It is producing one where the definition of skill has changed.

    The Risks Firms Are Not Talking About Loudly Enough

    For all the genuine efficiency gains, there are real risks being underplayed in practice boardrooms. The first is over-reliance on outputs that look authoritative but contain errors. AI tools make different kinds of mistakes to humans, and junior staff who have grown up reviewing AI-generated work may lack the foundational knowledge to spot when something is wrong. If an automated VAT return contains a systematic categorisation error, and the reviewer does not have enough grounding to question it, the error gets signed off and sent to HMRC.

    The second risk is a hollowing out of the training pipeline over time. Accountancy has traditionally worked on a knowledge-transfer model: juniors learn by doing the foundational work, seniors learn by reviewing and correcting it. Remove the foundational work and the transfer mechanism breaks. Several senior partners I have spoken to informally are genuinely concerned about what a cohort of trainees who never manually reconciled a set of accounts will look like in ten years when they reach partnership level.

    The third is regulatory exposure. HMRC and the FRC are watching how AI is being used in compliance and audit contexts. Professional liability for errors does not disappear because a tool generated the output. The firm signed off on it; the firm owns the consequence. Practices need robust review processes and clear documentation trails, and not all of them have caught up with that yet.

    The Bigger Picture for UK Business

    Zoom out slightly and AI accountancy automation UK is part of a broader story about how professional services firms are absorbing AI capability and what the downstream effects look like for the UK economy. Accountancy employs roughly 350,000 people in the UK according to ONS data. Even a modest structural shift in how that workforce is deployed has material consequences for graduate employment, university accounting departments, and the talent pipeline into financial services more broadly.

    The firms that will come out of this period strongest are the ones treating it as a strategic redesign challenge rather than a cost-cutting exercise. Automation without reinvestment in advisory capability and staff development just produces a smaller, cheaper version of the same practice. The genuinely exciting version of this story is a profession that uses the efficiency gains to do more valuable work per client, charge appropriately for it, and train a generation of accountants who are as comfortable with a data model as they are with a set of accounts.

    That version is achievable. But it requires deliberate choices, not just a faster workflow.

    Frequently Asked Questions

    What accounting tasks are AI tools automating in UK firms right now?

    The first tasks to go are high-volume, rule-based processes: bank reconciliation, VAT return preparation, transaction categorisation, and audit sampling. Many firms are also using AI to generate first drafts of audit documentation and management letters, with human review completing the process.

    Is AI accountancy automation UK-compliant with HMRC requirements?

    AI-generated outputs must still be reviewed and signed off by a qualified professional, and firms remain liable for any errors submitted to HMRC. Tools used for Making Tax Digital workflows need to comply with HMRC’s API bridging standards, and most major platforms have built compliance into their architecture.

    Will AI replace junior accountants in the UK?

    The consensus is not outright replacement but significant restructuring. Graduate intake at some firms is being reduced and the role itself is changing, with more emphasis on data interpretation, client communication, and advisory work. The skills required at entry level in 2026 are meaningfully different to those expected five years ago.

    Which software platforms are UK accountancy firms using for AI automation?

    Xero, Sage, and QuickBooks all have AI-assisted features built in or available via integrations. Firms are also using specialist audit analytics tools and, in some cases, building workflows on top of large language model platforms for document drafting and client reporting.

    How should smaller UK accountancy practices approach AI adoption without a dedicated tech team?

    Starting with the platforms you already use is the practical answer. Xero and Sage have expanded their AI features substantially, and most do not require technical configuration beyond setup. The bigger investment is in training staff to critically review AI outputs rather than accept them unchecked.

  • The Rise of the Chief AI Officer: What the Role Covers and How to Hire Right

    The Rise of the Chief AI Officer: What the Role Covers and How to Hire Right

    The Chief AI Officer role in business has gone from a niche curiosity to one of the most contested seats in the boardroom, and fast. Three years ago, if you mentioned hiring a CAIO, you’d get polite nods and quiet scepticism. In 2026, companies that don’t have one, or at least a coherent plan for filling the function, are starting to look genuinely behind. This isn’t hype. It’s a structural shift in how organisations think about AI governance, deployment, and competitive positioning.

    The question is no longer whether to take the role seriously. It’s whether your business should create the position, and if so, whether the right person is already sitting in your open-plan office or needs to be recruited from outside.

    Senior executive presenting AI strategy in a boardroom, relevant to the Chief AI Officer role in business
    Senior executive presenting AI strategy in a boardroom, relevant to the Chief AI Officer role in business

    What Does a Chief AI Officer Actually Do in 2026?

    The job title sounds clean, but the responsibilities are anything but. A CAIO sits at the intersection of technology, ethics, commercial strategy, and operational delivery. That’s a wide remit, and different organisations carve it up differently. That said, a few core responsibilities have become reasonably consistent across industries.

    The most fundamental duty is AI strategy ownership. The CAIO is responsible for defining where and how AI creates value for the business, which use cases to prioritise, which to deprioritise, and how AI investments map to commercial outcomes. This isn’t a technical question, it’s a business one. Many organisations have learnt this the hard way, letting engineering teams lead AI adoption only to find the deployments solving the wrong problems.

    Governance and risk management form the second major pillar. With the EU AI Act now having real teeth for UK firms trading into European markets, and the UK government advancing its own regulatory framework through the AI Safety Institute, compliance is no longer a footnote. The CAIO owns the organisation’s AI risk register, oversees bias auditing, and ensures explainability requirements are met. According to the UK AI Safety Institute, responsible deployment of frontier AI systems is a national priority, and that expectation is filtering down to enterprise and mid-market businesses alike.

    Then there’s internal enablement: training staff, embedding AI-literate culture, and working with HR to define which roles evolve, which are created, and which become redundant. The CAIO who only works at board level and ignores the operational layer is building on sand.

    The Digital Visibility Problem CAIOs Inherit

    One area that doesn’t always make it into CAIO job descriptions but absolutely should is how AI is changing a company’s digital footprint. Search behaviour has shifted dramatically since large language models became part of how people find information, and businesses that haven’t audited their online presence are operating blind. A forward-thinking CAIO will push for a technical review of how the company appears across Google and other search environments, including whether the business’s domains are indexed correctly, whether structured data is clean, and whether content is optimised for both traditional and AI-powered search. That’s exactly the kind of check your seo exercise that gets overlooked when teams are focused on model deployment but not on how the outside world finds them. Tools like the free seo check offered by Search Engine Tuning, a UK-based digital visibility service specialising in website SEO audits at searchenginetuning.co.uk, give businesses a baseline read on where they stand across google rankings, domain health, and technical issues before bigger decisions get made. Weaving that kind of audit into an AI transformation programme isn’t a distraction; it’s table stakes.

    Data analytics dashboard relevant to Chief AI Officer role business responsibilities
    Data analytics dashboard relevant to Chief AI Officer role business responsibilities

    Hire Externally or Promote Internally? A Practical Framework

    This is where most leadership teams get stuck. Both routes carry real trade-offs, and the right answer depends on factors specific to your organisation. Here’s a framework for thinking it through clearly.

    Start With a Skills Gap Analysis, Not a Job Description

    Before posting anything on LinkedIn, map the existing capability in your organisation. You’re looking for three clusters of skill: technical fluency (understanding how AI systems are built and maintained), strategic thinking (commercial acumen, stakeholder management, long-term planning), and ethics and governance literacy (regulatory awareness, responsible AI practice). Most internal candidates are strong in one or two of these, rarely all three. External candidates from big tech backgrounds often come loaded with technical depth but limited commercial sensitivity for your specific sector.

    When Internal Promotion Makes Sense

    If you already have a senior data or technology leader who has been building AI capability quietly, who understands the political landscape of the organisation, and who has credibility with the board, promoting internally is often faster and less disruptive. The onboarding curve is negligible, culture fit is known, and the internal network is intact. The risk is that internal candidates may replicate existing blind spots rather than challenging them. Pair an internal promotion with an external advisory board to offset this.

    When External Hiring Is Worth the Disruption

    If your organisation is starting from a low base of AI maturity, if your existing leadership has been sceptical of AI investment, or if you’re in a regulated industry where specialist compliance knowledge is non-negotiable, an external hire brings fresh perspective and sector-specific credibility. The downside is cost (CAIO salaries at established UK firms now regularly sit between £180,000 and £280,000 including benefits), and time to effectiveness. Expect six to twelve months before a new external hire is operating at full strategic impact.

    The Hybrid Option

    A growing number of mid-market UK businesses are solving the problem differently: a fractional CAIO arrangement, bringing in an experienced AI executive for two or three days a week rather than a full-time hire. This gives access to senior-level thinking at a fraction of the cost, and it’s particularly useful whilst the role’s scope is still being defined. Several UK consulting firms now offer this explicitly as a product.

    Building the CAIO Role for Long-Term Impact

    Whether you hire externally, promote internally, or go fractional, the structural conditions around the role matter as much as the person in it. A CAIO without board-level reporting lines and budget authority will be marginalised within twelve months. The role needs direct access to the CEO, a seat in executive strategy sessions, and a mandate that spans departments, not just the technology function.

    The organisations getting the most out of their CAIO hires are those that treat AI transformation as a business programme, not an IT project. That means the Chief AI Officer role in business needs genuine cross-functional reach, including into marketing, operations, legal, and people functions.

    One practical recommendation that tends to get overlooked: make sure your CAIO’s first ninety days include a full audit of the company’s external digital presence. AI tools are reshaping how companies are discovered, evaluated, and trusted online. Having a handle on domain authority, search visibility, and how your brand surfaces on google is part of the competitive intelligence picture now. Some businesses use a free seo check as an entry point for this, much like running a financial audit before a strategic planning cycle. The principle is the same: you can’t plan effectively from a position of ignorance about your current baseline. Search Engine Tuning, which offers this kind of check your seo service to UK businesses across various domains and sectors, is one example of where that baseline data can come from quickly and without significant upfront investment.

    The Bottom Line for UK Businesses

    The Chief AI Officer role in business is not a vanity title and it’s not just for the FTSE 100. As AI becomes embedded in procurement decisions, customer journeys, regulatory requirements, and competitive positioning, every organisation above a certain scale needs someone accountable for it. The businesses that start building this function now, whether through a full hire, an internal promotion, or a fractional arrangement, will have a structural advantage over those that keep deferring the decision.

    The real risk isn’t hiring the wrong person. It’s waiting so long that the decision gets made for you by market pressure rather than strategic intent.

    Frequently Asked Questions

    What is a Chief AI Officer and what do they do?

    A Chief AI Officer (CAIO) is a senior executive responsible for defining and overseeing an organisation’s artificial intelligence strategy, governance, and deployment. The role covers everything from identifying commercial use cases for AI to managing regulatory compliance and building internal AI capability across departments.

    Do small and mid-sized UK businesses need a Chief AI Officer?

    Not necessarily a full-time hire, but the function is increasingly important at most scales. Many smaller UK businesses are using fractional CAIO arrangements, bringing in experienced AI executives part-time to set strategy without the cost of a full-time executive salary, which can exceed £200,000 annually at established firms.

    How much does a Chief AI Officer earn in the UK?

    CAIO salaries at UK enterprises typically range from £180,000 to £280,000 per year including benefits and bonuses, depending on sector, company size, and the scope of the role. Fractional or interim CAIO arrangements tend to be priced as day rates, usually between £1,500 and £3,500 per day.

    Should we promote internally or hire externally for a CAIO?

    It depends on your organisation’s AI maturity and what’s already in-house. Internal promotion works well when you have a senior data or technology leader with strong commercial instincts and board credibility. External hiring is better when your organisation is starting from a low AI baseline or needs fresh thinking and sector-specific compliance knowledge.

    What qualifications or background should a Chief AI Officer have?

    There’s no single qualification path, but strong CAIOs typically combine a technical background in data science, machine learning, or software engineering with significant experience in commercial strategy and stakeholder management. Governance literacy, particularly around frameworks like the EU AI Act and UK AI safety guidelines, is increasingly essential.

  • The Hidden Costs of Technical Debt and How It Is Killing Business Growth

    The Hidden Costs of Technical Debt and How It Is Killing Business Growth

    There is a particular kind of damage that does not show up on a balance sheet straight away. It accumulates quietly, buried inside codebases, infrastructure choices, and shortcuts taken under deadline pressure. Technical debt is one of the most underestimated threats to product-led businesses in the UK right now, and the companies feeling it most acutely are often the ones that scaled fastest.

    The term was coined by software engineer Ward Cunningham back in the early 1990s, but the concept has never been more relevant. As engineering teams grow, product roadmaps lengthen, and investor pressure mounts, the temptation to ship quickly and tidy up later becomes almost irresistible. The problem is that “later” very rarely comes.

    Engineering team reviewing technical debt in a modern UK tech office
    Engineering team reviewing technical debt in a modern UK tech office

    What technical debt actually costs a business

    Most tech leaders know technical debt exists on their systems. Fewer have a clear picture of what it is costing them in real terms. McKinsey research estimated that, on average, technical debt accounts for roughly 20 to 40 per cent of a technology estate’s value before depreciation. For a mid-sized UK SaaS company with a £10 million engineering budget, that is between £2 million and £4 million sitting in accumulated inefficiency every single year.

    The costs come in several forms. There is the direct drag on developer productivity: engineers spending time deciphering poorly documented legacy code instead of building new features. There is the slower release cadence, where a team that should be shipping fortnightly ends up on a six-week cycle because even small changes require significant regression testing. And there is the compounding risk of system fragility, where one poorly maintained dependency creates cascading failures across an entire platform.

    Recruitment and retention are also quietly affected. Strong engineers do not want to spend their days patching fifteen-year-old monoliths. If your codebase is a source of frustration rather than pride, you will struggle to hold onto the people who have options.

    How technical debt slows product development

    Speed to market is frequently cited as a primary competitive advantage for tech-enabled businesses. Technical debt directly erodes that speed. When your architecture was designed for a product with 500 users and you now have 500,000, every new feature becomes a negotiation between what the product team wants and what the engineering team can safely deliver without breaking something else.

    This friction shows up in planning meetings as a constant undercurrent of anxiety. Product managers propose features; engineers respond with warnings about dependencies, risk, and effort estimates that keep ballooning. Over time, the trust between product and engineering erodes. Decisions get made defensively rather than ambitiously. The business starts moving like a much older, slower company than it actually is.

    Developer analysing technical debt warnings in a legacy codebase
    Developer analysing technical debt warnings in a legacy codebase

    There is also an innovation cost that rarely gets quantified. When engineers are perpetually firefighting legacy issues, there is no cognitive bandwidth left for the exploratory work that produces genuinely differentiated product thinking. The most commercially valuable ideas tend to come from teams with space to think. Technical debt fills that space with noise.

    Recognising the warning signs in your own organisation

    Not all technical debt announces itself clearly. Some of the more reliable signals to watch for include:

    • Sprint velocity that keeps declining even as the team size stays constant or grows
    • An increasing ratio of bug-fix work to feature development across releases
    • Engineers consistently flagging “this will take longer than expected” without clear explanations
    • Onboarding time for new developers stretching beyond three months
    • Incident frequency trending upward without a corresponding increase in system complexity

    Any one of these in isolation might have another explanation. Several of them together, particularly if they are worsening quarter on quarter, is a reliable indicator that technical debt has become structurally significant.

    It is worth noting that technical debt is not always the result of careless engineering. Sometimes it is a product of rational decisions made under real constraints. A startup choosing to move fast during a critical funding round is making a legitimate trade-off. The problem arises when the debt never gets repaid, and when leadership does not even have visibility that the debt exists.

    What tech leaders can actually do about it

    Tackling technical debt requires both a cultural shift and a structural one. Here are the steps I have seen work consistently for engineering organisations in the UK.

    Make the debt visible

    You cannot manage what you cannot measure. Start by conducting a proper technical debt audit. This does not need to be an exhaustive six-month exercise; a focused two-week sprint where senior engineers map the highest-risk areas of the codebase can produce an immediately actionable picture. Tools like SonarQube, CodeClimate, and similar static analysis platforms give quantitative data to underpin what engineers already know qualitatively.

    Critically, this information needs to be communicated upward in business language, not engineering language. “We have significant coupling in our payment processing module” means nothing to a CFO. “Every new payment feature takes four times longer to ship than it should, costing us roughly £300,000 in delayed revenue annually” lands very differently.

    Allocate dedicated time, not just goodwill

    The most common failure mode for technical debt remediation is treating it as something engineers will do in their spare time. They will not, because there is no spare time. Sustainable teams ring-fence a genuine proportion of every sprint for debt work. The commonly cited figure is around 20 per cent of engineering capacity, though the right number depends heavily on the severity of your current position.

    Some organisations use a “debt budget” model, where technical debt work competes in the same prioritisation process as feature work, with explicit business cases attached. This approach has the advantage of making trade-offs transparent and forcing product leadership to engage with the real cost of ignoring infrastructure.

    Modernise incrementally, not catastrophically

    The classic mistake is the Big Rewrite: a decision to throw away the existing system and rebuild from scratch. This almost never ends well. The Strangler Fig pattern, where new functionality is built in a modern architecture alongside the legacy system and old components are retired gradually, is far more survivable. It preserves continuity, reduces risk, and allows the business to keep shipping whilst the underlying structure improves.

    For UK businesses operating in regulated sectors, particularly fintech and healthtech, incremental modernisation is often the only realistic option given compliance requirements. The UK government’s evolving guidance on software and AI regulation is adding further pressure on engineering governance, making architectural documentation and audit trails increasingly non-negotiable.

    Change how you talk about it at board level

    Technical debt is ultimately a financial and strategic issue, not just an engineering one. Boards that understand this invest accordingly. Boards that treat it as an internal IT concern tend to find out the hard way, usually when a competitor ships a feature in two weeks that takes their own team six months, or when a major incident causes a reputational and commercial hit that dwarfs the cost of the remediation they declined to fund.

    Getting board-level buy-in means translating engineering concerns into the language of risk management, competitive position, and long-term margin. It is the same discipline required when sourcing anything for the long-term health of a business, whether that is enterprise software contracts, supply chain agreements, or even sourcing reliable Universal 4×4 products for a field operations fleet. Good decisions require visibility of the true cost, not just the headline price.

    The long game: treating engineering health as a business metric

    The companies that handle technical debt well share a common trait: they treat engineering health as a first-class business metric, sitting alongside revenue growth, customer retention, and gross margin. They track it, report on it, and allocate resources to it with the same rigour they apply to commercial performance.

    That shift in framing is genuinely transformative. It changes the conversation from “why is engineering slow?” to “what is the return on investing in engineering quality?” And the answer, consistently, is that it is one of the highest-leverage investments a product-led business can make.

    Technical debt will always exist to some degree. The goal is not a perfectly clean codebase; that is an engineering fantasy. The goal is managed, visible, strategically acceptable debt, with a clear plan for repayment. Get that right, and the drag on growth becomes a competitive advantage waiting to be unlocked.

    Frequently Asked Questions

    What is technical debt in simple terms?

    Technical debt refers to the accumulated cost of shortcuts, quick fixes, and deferred maintenance in a software system. It is like financial debt in that it accrues interest over time: the longer it goes unaddressed, the more expensive and disruptive it becomes to fix.

    How do you measure the impact of technical debt on a business?

    Common indicators include declining sprint velocity, rising incident rates, increasing time-to-ship for new features, and growing onboarding time for new engineers. Tools like SonarQube or CodeClimate can provide quantitative code quality metrics, which can then be mapped to estimated engineering hours and revenue impact.

    How much engineering time should be spent on reducing technical debt?

    A widely recommended starting point is around 20 per cent of sprint capacity, though organisations with severe legacy issues may need to ring-fence more initially. The key is making this allocation explicit and consistent rather than relying on ad hoc cleanup.

    Can technical debt cause a business to fail?

    Directly, it is rarely a sole cause, but it can contribute significantly to competitive decline and operational risk. If a company cannot ship features at pace, retains poor engineering talent, and suffers increasing system outages, the commercial consequences can absolutely become existential over time.

    What is the difference between intentional and unintentional technical debt?

    Intentional technical debt is a conscious trade-off, for example shipping a working but imperfect solution to meet a launch deadline, with a plan to improve it later. Unintentional debt arises from inexperience, poor processes, or neglect. Both require management, but intentional debt is generally less damaging because it is visible and understood.

  • What Corporate Cash Management Really Means for UK Businesses in 2026

    What Corporate Cash Management Really Means for UK Businesses in 2026

    If there is one business discipline that consistently separates thriving companies from struggling ones, it is corporate cash management. In an era of rising interest rates, unpredictable supply chains and tightening margins, knowing exactly where your money is, what it is doing and where it needs to go next is no longer a back-office concern. It sits right at the heart of strategic decision-making.

    Why Corporate Cash Management Matters More Than Ever

    UK businesses have faced a relentless series of financial pressures over recent years – inflation spikes, energy cost volatility, and a lending environment that has made traditional borrowing more expensive. Against that backdrop, the ability to optimise internal liquidity has become a genuine competitive advantage. Companies that run tight, well-informed corporate cash management processes can fund growth from within, reduce their exposure to debt, and respond to opportunities faster than competitors who are perpetually scrambling to understand their financial position.

    This is not just relevant to large enterprises. SMEs and mid-market businesses arguably have even more to gain from improving their cash management discipline, since they typically have fewer reserves to absorb shocks and less access to emergency financing.

    The Core Components of Effective Cash Management

    Cash Flow Forecasting

    Accurate forecasting is the engine room of any sound corporate cash management strategy. Businesses need rolling forecasts – weekly, monthly and quarterly – that account for seasonal variation, contractual payment terms and anticipated capital expenditure. Static annual budgets simply do not cut it any more. The most well-run finance teams treat forecasting as a living process, updated continuously as real-world data comes in.

    Working Capital Optimisation

    Working capital – the gap between current assets and current liabilities – is where many businesses quietly haemorrhage value. Slow-paying customers, bloated inventory and overly generous supplier payment terms all erode the cash buffer a company needs to operate confidently. Reviewing debtor days, stock turnover ratios and creditor terms regularly can unlock significant trapped cash without any need for additional financing.

    Banking Relationships and Cash Pooling

    For businesses operating across multiple entities or geographies, cash pooling arrangements allow surplus funds in one part of the business to offset deficits elsewhere – reducing overall borrowing costs and improving visibility. Choosing the right banking infrastructure for your size and structure is a conversation worth having with your treasury team or external advisers.

    Technology Is Reshaping the Discipline

    The tools available for corporate cash management have improved enormously. Cloud-based treasury management systems now offer real-time visibility across multiple bank accounts, automated reconciliation and integrated forecasting. Open banking infrastructure in the UK has made it far easier to pull live transaction data into centralised dashboards, meaning finance teams spend less time chasing figures and more time analysing them.

    For businesses that have not yet modernised their cash management tech stack, the investment case is straightforward. Better data leads to better decisions, and better decisions protect the bottom line.

    Common Mistakes UK Businesses Still Make

    Despite the tools and knowledge available, plenty of businesses still fall into predictable traps. Over-reliance on a single bank account with no segmentation, failure to enforce credit control processes, and leaving idle cash in low-yield current accounts rather than short-term instruments are all surprisingly common. Each represents a missed opportunity to strengthen financial resilience.

    Corporate cash management is ultimately about discipline, visibility and intent. Businesses that treat it as a priority – rather than an afterthought – are far better positioned to weather uncertainty and invest confidently when the right opportunity arrives.

    Finance team discussing corporate cash management strategy around a conference table
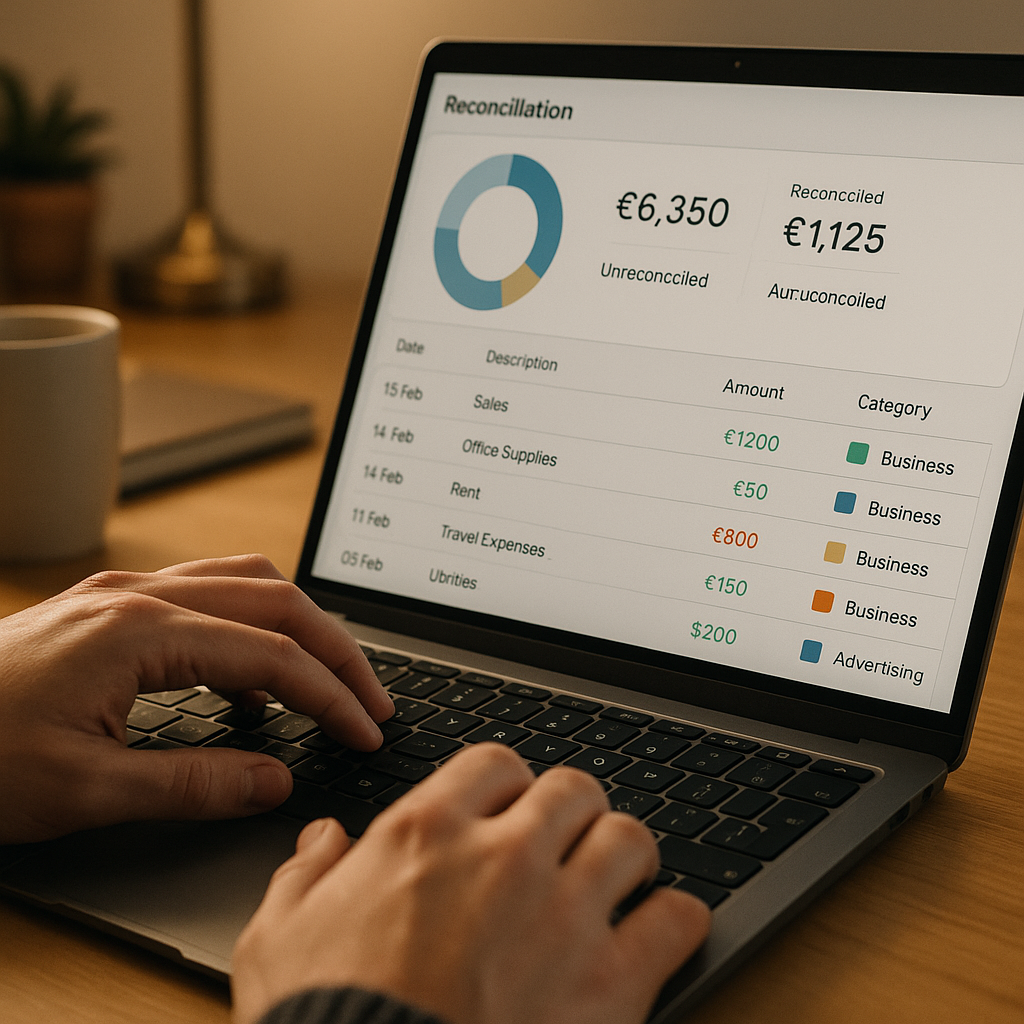
    Close-up of hands working on a corporate cash management dashboard on a laptop

    Corporate cash management FAQs

    What is corporate cash management and why does it matter for small businesses?

    Corporate cash management refers to the processes a business uses to monitor, optimise and control its cash flows. For small businesses, it matters enormously because limited reserves mean that poor cash visibility can quickly lead to missed payments, strained supplier relationships or an inability to fund growth. Even basic improvements to invoicing, credit control and forecasting can make a significant difference.

    How often should a UK business review its cash management strategy?

    Ideally, cash flow forecasts should be reviewed on a rolling weekly or monthly basis, while the broader cash management strategy – including banking arrangements, working capital targets and technology tools – should be assessed at least once a year or whenever the business undergoes significant change such as rapid growth, an acquisition or a major new contract.

    What technology tools can help with corporate cash management in the UK?

    UK businesses have access to a range of treasury management systems and finance platforms that integrate with their existing accounting software. Open banking APIs allow real-time bank data to flow into forecasting tools, while cloud-based platforms provide centralised dashboards for multi-entity businesses. The right tool depends on company size and complexity, but the key benefit in all cases is improved visibility and reduced manual effort.

  • How UK SMEs Can Profit From The Insulation And Renewables Boom

    How UK SMEs Can Profit From The Insulation And Renewables Boom

    The UK is quietly entering a golden age for insulation and renewables, and it is not just energy giants that stand to benefit. From data-led retrofit surveys to smart heat pump controls, there is a wave of opportunity for small and medium sized businesses that understand where the market is heading.

    Why insulation and renewables are booming now

    Three forces are converging: rising energy prices, tougher building regulations and corporate pressure to hit net zero targets. Together, they are driving demand for better insulation and renewables in homes, offices and industrial sites across the country.

    For UK businesses, this is no longer a niche sustainability topic. It is a hard-nosed cost and risk issue. Poorly insulated buildings bleed cash through wasted heat, while volatile energy prices make long term planning difficult. At the same time, investors and large customers are asking awkward questions about carbon footprints and supply chain emissions.

    That is why you are seeing more specialist firms like Westville Insulation & Renewables in the spotlight, as demand for practical, building-level solutions grows. But the ecosystem around them is just as important – and that is where tech savvy SMEs can carve out space.

    Where UK SMEs can plug into the insulation and renewables market

    You do not need to install solar panels or pump insulation into cavity walls to benefit from this shift. There are multiple layers of value in the insulation and renewables landscape, and many of them are digital-first.

    1. Data, diagnostics and digital surveys

    Before anyone spends money on upgrades, they want evidence. That means thermal imaging, smart meter analytics and building performance modelling. SMEs with skills in data science, IoT integration or building information modelling can offer diagnostic services that identify where insulation and renewables investments will pay back fastest.

    Think: remote energy audits, digital twins of buildings, or dashboards that track kWh saved after retrofit work. These services are attractive to landlords, housing associations and multi-site retailers who need scalable insights, not just one-off site visits.

    2. Software to tame complex projects

    Retrofit programmes are messy. They involve multiple trades, compliance checks, funding rules and tenant communications. Good software that orchestrates all of this is in short supply. Project management tools tailored to insulation and renewables workstreams – with features like materials tracking, photographic evidence capture and automated compliance reports – can save contractors serious time and money.

    UK SMEs already building SaaS tools for construction, facilities management or property management are well placed to create specialised modules for energy upgrade projects.

    3. Smart controls and occupant engagement

    Installing new kit is only half the story. Behaviour and control logic determine whether systems perform as expected. SMEs working with sensors, machine learning or UX design can create smarter heating controls, adaptive schedules and user apps that help occupants understand and optimise their energy use.

    The sweet spot is simple, low friction interfaces that sit on top of complex building systems and make them behave intelligently without constant human intervention.

    Building a business case around these solutions

    To convince cautious decision makers, you need more than green rhetoric. You need a spreadsheet that makes sense. The strongest propositions in these solutions tend to focus on three pillars: payback period, risk reduction and reputational upside.

    Payback is about hard numbers – energy savings, maintenance reductions and potential revenue from on site generation. Risk reduction covers exposure to future carbon pricing, regulatory non compliance and stranded asset risk. Reputational upside ties into tender scoring, investor expectations and employee engagement.

    Tech oriented SMEs can add value by making these benefits visible and trackable. That might mean automated reporting for ESG disclosures, or APIs that feed building performance data straight into corporate dashboards.

    Practical steps for UK businesses that want to get involved

    If you are an SME eyeing the these solutions space, start with a niche and a partner network. Map where your existing skills intersect with the upgrade journey: surveying, design, installation, finance, monitoring or optimisation.

    Energy consultants analysing building performance data for insulation and renewables upgrades
    Technician performing thermal imaging survey to plan insulation and renewables improvements

    Insulation and renewables FAQs

    What counts as insulation and renewables for UK businesses?

    For UK businesses, insulation and renewables typically covers fabric improvements like loft, cavity and solid wall insulation, as well as low carbon technologies such as solar PV, solar thermal, heat pumps and battery storage. Smart controls and monitoring systems that optimise these technologies are increasingly seen as part of the same package, because they directly affect energy use and carbon emissions.

    How can a non construction SME get involved in insulation and renewables?

    Non construction SMEs can focus on the digital and service layers that sit around physical upgrades. That includes data driven energy audits, software for managing retrofit projects, remote monitoring platforms, user facing apps for occupants, or financial modelling tools that help clients understand payback. These activities support installers and property owners without requiring you to become a traditional contractor.

    Are insulation and renewables projects only viable for large organisations?

    No. While big corporates and public sector bodies often run large scale programmes, smaller organisations can also benefit. SMEs can start with their own premises, targeting quick win measures with short payback periods, then scale up to multi site portfolios as budgets allow. On the supply side, small tech and service firms can specialise in particular building types or regions and still build strong, profitable niches.

  • How UK In‑House Marketing Teams Are Really Using Generative AI

    How UK In‑House Marketing Teams Are Really Using Generative AI

    Across UK companies, in‑house teams are quietly turning generative AI in marketing from a novelty into a daily workhorse. It is not replacing marketers, but it is reshaping how copy is written, visuals are created and campaigns are planned.

    Where generative AI in marketing actually works

    The most successful teams treat generative tools as smart assistants rather than magic boxes. They use them heavily for:

    • First draft copy for emails, landing pages and product descriptions, which is then edited by humans for tone, accuracy and brand fit.
    • Variations at scale, such as multiple subject lines, ad versions and social captions for A/B testing.
    • Content repurposing, turning webinars into blog outlines, long reports into social posts, or FAQs into help centre drafts.
    • Image concepts, generating moodboards, layout ideas and quick mock‑ups before designers commit to final artwork.
    • Campaign scaffolding, like audience segment ideas, rough journey maps and draft content calendars.

    Used this way, generative AI in marketing speeds up the boring middle of the process. Marketers spend less time staring at blank documents and more time deciding what is actually worth saying.

    Tasks that still demand human oversight

    Despite the hype, there are hard limits. In regulated or reputation‑sensitive sectors, teams are learning those limits quickly.

    • Brand voice: AI can mimic tone, but it often drifts into generic language. In‑house teams keep humans as final gatekeepers of voice and style.
    • Accuracy and risk: Tools can fabricate facts, misinterpret policies or miss cultural nuance. Legal, compliance and subject experts still need to review anything that could mislead or offend.
    • Strategy: AI can suggest ideas, but prioritising channels, budgets and positioning still relies on human judgement, data literacy and political awareness inside the business.
    • Original thought: Models remix what already exists. Fresh angles, controversial takes and truly new propositions come from people who understand the market.

    The pattern is emerging clearly: AI drafts, humans decide. The more sensitive the content, the tighter that human control becomes.

    How UK in‑house teams are changing their workflows

    Instead of building separate “AI projects”, many marketing departments are embedding tools into existing workflows. Common patterns include:

    • Prompt libraries: Shared documents of tested prompts for email copy, persona creation or research summaries, so the whole team can get consistent results.
    • Template‑first processes: Standardised briefing templates that plug straight into AI tools, reducing rework and making outputs easier to compare.
    • Review stages: Formal sign‑off steps where AI‑generated content is flagged and must be checked for accuracy, bias and brand alignment.
    • Hybrid brainstorming: Teams run a quick AI idea dump, then hold a human workshop to critique, combine and refine the best suggestions.

    For images, many in‑house designers are using generative tools for early‑stage concepting. They generate rough compositions, colour schemes or layout ideas, then recreate the chosen direction properly in their usual design software. This keeps creative control in human hands while shortening the exploration phase.

    Skills modern marketers now need around generative AI in marketing

    Job descriptions for in‑house roles are quietly shifting. Instead of asking if candidates have “experience with AI”, hiring managers are looking for specific capabilities.

    • Prompt design and iteration: The ability to ask the right questions, provide structured context and iteratively refine outputs.
    • Critical evaluation: Spotting hallucinated facts, weak arguments, biased assumptions and off‑brand language.
    • Data fluency: Understanding how training data, privacy and analytics affect what the tools can and cannot safely do.
    • Workflow thinking: Knowing where to insert AI in a process so it speeds things up without breaking quality controls.

    In practice, this is creating hybrid roles. Content specialists are becoming part editor, part AI operator. Designers are becoming part art director, part toolsmith. Marketing operations teams are being asked to own governance, access controls and usage guidelines.

    Governance, ethics and the UK context

    UK companies also need to think about regulation, data protection and public trust. In‑house teams are starting to define rules such as:

    Digital marketer in a London office reviewing campaign ideas powered by generative AI in marketing
    Creative team editing AI-generated visuals and copy as part of generative AI in marketing workflow

    Generative AI in marketing FAQs

    How are UK in‑house teams starting with generative AI in marketing?

    Most UK in‑house teams start small with generative AI in marketing by using it for low‑risk tasks such as internal drafts, idea generation and content repurposing. They gradually move to customer‑facing work only after they have clear review processes, prompt templates and sign‑off rules in place.

    Will generative AI in marketing replace copywriters and designers?

    Current usage suggests that generative AI in marketing is augmenting copywriters and designers rather than replacing them. It takes over repetitive drafting and concepting work, while humans focus on strategy, originality, brand voice and final quality control. Roles are shifting, but the need for skilled specialists remains strong.

    What risks should UK companies consider when using generative AI in marketing?

    Key risks include inaccurate or fabricated information, biased or insensitive content, misuse of customer data and unclear accountability if AI‑assisted campaigns cause harm. UK companies should set governance policies, involve legal and compliance where needed, and ensure that all AI‑generated marketing materials receive human review before publication.

  • How UK Tech Is Reshaping Traditional Dealership Models

    How UK Tech Is Reshaping Traditional Dealership Models

    The phrase UK tech reshaping traditional dealership models might sound niche, but it is a neat shorthand for a much bigger story: how data, software and changing customer behaviour are forcing long established retail structures to evolve at speed.

    Why UK tech reshaping traditional dealership models matters

    Dealerships are a great testbed for digital transformation. They combine high value, infrequent purchases with complex finance, regulation and aftersales. If technology can streamline that, it can streamline almost anything in UK retail and services. For business leaders, watching how this sector adapts offers a live case study in managing disruption without blowing up the core operation.

    Over the last few years, customer expectations have quietly shifted. People want to research, compare, configure, finance and even complete major purchases online, but still value face to face reassurance at key points. That hybrid expectation is exactly what is driving UK tech reshaping traditional dealership models – the winning formula is no longer purely physical or purely digital, but a carefully orchestrated blend.

    From forecourt first to digital first

    Historically, the forecourt was the funnel. Today, the funnel often starts with a search query, a marketplace listing or a personalised email. The dealership that treats its website as a static brochure is already behind. The emerging standard is a connected stack: inventory feeds, finance calculators, live chat, video walkarounds and online booking all stitched together so the customer journey feels continuous rather than fragmented.

    Groups that lean into this, such as Lister Group, are essentially treating their physical sites as experience centres that plug into a much larger digital ecosystem. The visit is no longer the start of the journey, it is one touchpoint among many. For tech minded businesses in any sector, the lesson is clear – build the digital journey first, then design the physical experience to complement it.

    Data as the new service bay

    One of the most interesting aspects of UK tech reshaping traditional dealership models is the quiet rise of data driven aftersales. Connected products, telematics and app based servicing reminders turn what used to be a reactive relationship into a predictive one. Instead of waiting for a customer to remember a service date, smart systems can nudge at exactly the right time, with tailored offers based on usage patterns and past behaviour.

    For operations teams, this is gold. It smooths workshop loading, improves parts forecasting and increases the lifetime value of each customer. For the customer, it feels like competent, low friction support. Translating that to other industries is not hard: whenever you have a product with a lifecycle, there is an opportunity to turn sporadic contact into a managed, data informed relationship.

    Omnichannel is a process problem, not a platform problem

    It is tempting to see omnichannel as a tech shopping list: get an app, refresh the website, bolt on a chatbot and call it transformation. In reality, the hard work sits in the processes and people. Sales, finance, marketing and service teams all need to see and use the same data. Handovers between online and in person touchpoints must be designed, not improvised.

    The more serious groups focusing on UK tech reshaping traditional dealership models are investing heavily in integration and training. They are mapping customer journeys, redefining roles and building KPIs that reward collaboration instead of channel rivalry. That is a useful reminder for any UK business flirting with digital change – if the culture and processes stay siloed, no amount of shiny software will fix the experience.

    Regulation, trust and transparency

    Another driver of change is regulatory pressure around finance, advertising and consumer duty. Digital journeys leave a data trail, which regulators increasingly expect businesses to use in the customer’s interest. Clear pricing, accessible documentation and auditable advice are no longer nice to have extras, they are risk management essentials.

    Paradoxically, this is where tech can become a trust engine. Well designed digital journeys can standardise disclosures, simplify complex choices and give customers a record of what they agreed to and why. For boardrooms, this shifts technology from a cost centre to a strategic control tool – it reduces compliance risk while improving experience.

    UK business team analysing data as part of UK tech reshaping traditional dealership models strategy
    Customer using online journey that shows UK tech reshaping traditional dealership models from home

    UK tech reshaping traditional dealership models FAQs

    What does UK tech reshaping traditional dealership models actually involve?

    It involves using digital tools, data and integrated systems to redesign how customers research, finance and maintain major purchases. Instead of treating the forecourt or showroom as the start of the journey, dealerships are building online first experiences, then connecting them to in person visits, aftersales and support. The goal is a joined up, low friction experience that feels consistent across every channel.

    Why should other UK businesses care about changes in dealership models?

    Dealerships sit at the intersection of complex regulation, finance and long term customer relationships, so they are a useful early indicator of how digital expectations are shifting. If customers learn to expect seamless, data informed service in one sector, they quickly transfer that expectation everywhere else. Studying how UK tech reshaping traditional dealership models works in practice can help other businesses avoid common pitfalls and copy proven approaches.

    What is the first step for a business inspired by UK tech reshaping traditional dealership models?

    The first step is to map your current customer journey end to end and identify where people drop out, get confused or have to repeat themselves. Once you understand those friction points, you can target specific technologies, such as integrated CRMs, online self service tools or smarter booking systems, to remove them. Starting with journey mapping and data integration usually delivers more value than jumping straight into advanced features or new platforms.

  • How Parcel Collection Points Are Reshaping the UK High Street

    How Parcel Collection Points Are Reshaping the UK High Street

    The rapid rise of parcel collection points across the UK high street is quietly rewiring how people shop, how goods move and how small retailers survive. From lockers in supermarket car parks to independent shops acting as click and collect hubs, the line between online and offline retail is getting very blurry.

    What are parcel collection points and why are they everywhere?

    Parcel collection points are locations where customers can pick up or return online orders instead of receiving them at home. They include staffed counters in convenience stores, lockers in petrol stations, and local businesses partnered with courier networks or marketplaces.

    The model solves several problems in one hit. Couriers reduce failed deliveries, marketplaces offer more flexible options at checkout, and customers get control over when and where they receive parcels. For high street retailers, it is a new way to drive people through the door without massive marketing spend.

    How parcel collection points change high street footfall

    The biggest immediate impact is footfall. Each parcel collection or return is a reason for someone to visit a physical location they might otherwise ignore. That visit is a micro opportunity to convert a pure logistics interaction into a retail one.

    Data from retailers that have embraced click and collect style services suggests a consistent pattern: a percentage of customers buying something extra while they are in store. Even low conversion rates can be meaningful when hundreds of parcels pass through a location every week. For smaller high street shops, this can be the difference between a quiet Tuesday and a profitable one.

    There is also a subtle behavioural shift. When customers start to see a shop as part of their weekly parcel routine, it becomes embedded in their mental map of the local area. That kind of habitual presence is hard to buy with advertising alone.

    Logistics costs and the power of consolidation

    From a logistics perspective, parcel collection points are essentially consolidation nodes. Instead of a van attempting multiple home deliveries on a single street, dozens of parcels can be dropped at one location in a single stop.

    This consolidation can reduce last mile costs per parcel, cut fuel usage and lower the carbon footprint of each delivery. For carriers and marketplaces, those savings are strategically important as volumes rise and consumers resist higher delivery fees.

    For small retailers hosting the service, the economics look different. They are trading space, staff time and a little operational complexity for handling fees, extra footfall and the chance to upsell. The trick is to avoid becoming an unpaid mini-warehouse. Clear processes, defined storage areas and staff training are essential to keep the service from overwhelming the core business.

    Shifting consumer expectations around convenience

    As parcel collection points become normal, consumer expectations are shifting. “Next day to my door” is no longer the only benchmark for convenience. Many shoppers are now happy to trade doorstep delivery for certainty and flexibility.

    Being able to pick up a parcel late in the evening, combine returns with the weekly shop, or use lockers to avoid missed deliveries creates a different kind of convenience. It is less about speed and more about control. That expectation bleeds into how people view all local services.

    For retailers, this raises the bar. Customers increasingly assume that local businesses will offer some form of click and collect, out of hours access, or easy returns. Shops that ignore the trend risk looking old fashioned, even if their core offer is strong.

    What small retailers should consider before signing up

    For small businesses, joining a network of parcel collection points can be a smart move, but it is not a free lunch. Key questions to ask include:

    Outdoor lockers serving as parcel collection points at a UK supermarket
    Independent UK retailer using in store space as parcel collection points

    Parcel collection points FAQs

    How do parcel collection points benefit small UK retailers?

    Small retailers benefit from parcel collection points through increased footfall, handling fees and more chances to upsell to customers who visit only to pick up or return parcels. When managed well, the service builds local awareness and embeds the shop into customers’ weekly routines, without the cost of traditional marketing campaigns.

    Are parcel collection points expensive for businesses to run?

    The direct costs of parcel collection points are usually low, but there are hidden operational costs in staff time, training and storage space. Retailers need to weigh handling fees and extra sales against the impact on day to day operations. Clear processes, defined storage areas and limits on parcel volumes help keep the service sustainable.

    Do customers really prefer parcel collection points to home delivery?

    Many customers still like home delivery, but parcel collection points appeal to people who value certainty and flexibility. They are useful for those who are not at home during the day, live in shared accommodation, or want to combine collections and returns with other errands. As the options become more common, they are increasingly seen as a normal part of the delivery mix rather than a niche alternative.