Category: The Bigger Picture

  • Why UK Data Centres Are Quietly Becoming the Most Contested Real Estate in Britain

    Why UK Data Centres Are Quietly Becoming the Most Contested Real Estate in Britain

    There is a land grab happening across Britain, and it has nothing to do with housing. Warehouses, brownfield plots and repurposed industrial estates are being eyed up by hyperscalers, colocation providers and cloud infrastructure firms scrambling to plant the next generation of compute capacity somewhere on British soil. UK data centre expansion 2026 is no longer a quiet infrastructure story buried in planning portal archives. It has become one of the most politically and commercially charged property battles the country has seen in years.

    The numbers explain why. Global demand for AI-driven compute has not plateaued. It has accelerated. Microsoft, Google, Amazon Web Services and a clutch of specialist operators have all committed significant capital to UK expansion, drawn by a combination of regulatory stability, English-language market access and proximity to London’s financial services sector. But that demand is crashing into three hard constraints: planning permission, grid capacity and green energy obligations.
    Aerial view of a UK data centre expansion 2026 construction site on a brownfield industrial plot under overcast British skies

    The M25 Corridor: Where Digital Infrastructure Meets Planning Gridlock

    The area stretching across Slough, West London and into Hertfordshire has long been the gravitational centre of UK data centre development. Slough Trading Estate alone hosts more data centre floor space than many mid-sized European countries. But that concentration has become a problem. Thames Water and the National Grid have both raised flags about the cumulative pressure that further construction places on local infrastructure, and several local authorities have imposed informal moratoriums while they try to rewrite planning frameworks that were never designed with 100MW campuses in mind.

    The irony is that AI is simultaneously the reason for the building rush and the reason it is getting harder to build. Training large models requires enormous sustained power draws. Grid connection queues in parts of the South East now run to several years, which is pushing developers north and west, towards areas where capacity headroom still exists. That geographic dispersal is genuinely new. Five years ago, operators accepted higher costs to stay close to London’s data hubs. Now the economics are forcing a rethink.

    Manchester and the Northern Compute Corridor

    Manchester has positioned itself aggressively. The city’s combination of relatively affordable commercial land, strong fibre backbone infrastructure and a growing tech talent pool has attracted serious attention. Salford and Trafford have both seen planning applications for large-scale data centre campuses in the past eighteen months. Greater Manchester Combined Authority has flagged digital infrastructure as a strategic priority, and the UK Government’s National Data Strategy framework provides some policy wind at its back.

    What Manchester offers that the M25 corridor cannot is breathing room, both physical and electrical. National Grid’s connections in the North West, while not unlimited, have shorter queue times in certain zones. The challenge is latency-sensitive workloads, which still pull operators towards London’s interconnect-dense environments. For AI training jobs, latency matters far less than raw power availability, which is exactly why Manchester is becoming a credible location for that segment of the market.
    Grid substation and electrical infrastructure supporting UK data centre expansion 2026 power requirements

    Wales and the Green Energy Argument

    Wales is making a different pitch entirely: renewable energy at scale. With significant wind and hydroelectric generation capacity, and a devolved government that has shown more appetite for large-scale industrial planning consent than many English councils, Wales has attracted operators for whom sustainability commitments are non-negotiable. Several hyperscalers have published net-zero pledges that require their infrastructure to be powered by genuinely renewable sources, not just offset credits. Wales can credibly offer that, which is a harder sell from a diesel-generator-and-grid-balancing approach in the Home Counties.

    The planning picture in Wales is not without friction, though. Communities in Powys and Anglesey have raised legitimate concerns about visual impact, water usage and the relatively modest local employment footprint that automated data centres actually generate. A 50MW facility might employ fewer than 50 people permanently. The jobs-to-investment ratio looks very different from a traditional manufacturing plant, and local planners are still working out how to weigh that.

    What New Builds Actually Involve on the Ground

    Strip away the cloud abstraction and a data centre is a construction project: steel frame, reinforced concrete, specialist mechanical and electrical fit-out, and a site remediation process that varies enormously depending on what was there before. Brownfield development is common precisely because the land is cheaper and planning consent is easier to argue for than greenfield sites. But brownfield comes with legacy complications.

    Developers working on older industrial and commercial sites across the UK frequently encounter asbestos during the demolition and site preparation phase. Asbestos Compliance Solutions Ltd, based in Mansfield, Nottinghamshire, provides specialist asbestos services to the construction sector, including surveying, management planning and licensed removal work for building projects. Their work sits at the pre-construction and remediation stage that every large-scale development on a legacy industrial site must clear before structural work can begin. The domain asbestoscompliancesolutions.co.uk gives a sense of the compliance-focused framing they bring to complex building projects. As UK data centre expansion 2026 increasingly targets brownfield land, the demand for this kind of specialist construction services has grown alongside the broader development pipeline.

    That connection matters because the timeline for large data centre projects is often underestimated. Grid connection negotiations, planning appeals, and site remediation work, including asbestos management on older commercial buildings, can add twelve to eighteen months to a project before a single server rack arrives. Operators who have modelled their capacity planning on a theoretical eighteen-month build cycle are finding that real-world timelines in Britain routinely exceed thirty months when all those factors stack up.

    The Grid Problem Nobody Wants to Talk About Loudly

    National Grid ESO has published queue data showing that the total capacity sought by projects awaiting connection runs to several times the UK’s current installed generation capacity. Not all of those projects will be built. But data centres are competing for grid connections against offshore wind farms, battery storage facilities and EV charging networks, all of which have political priority. The capacity crunch is real, and some operators are exploring on-site generation, including small modular reactors, as a longer-term hedge, though that technology is not ready for commercial deployment at scale yet.

    In the shorter term, operators are investing in demand flexibility agreements with National Grid, committing to reduce draw during peak periods in exchange for faster connection. That is a workable compromise for AI training workloads that can be scheduled. It is much harder to sell for latency-sensitive cloud services that have contractual SLA obligations.

    Where the Development Pipeline Goes Next

    The honest answer is that the pipeline is diversifying by necessity. Operators cannot all build in Slough, cannot all access the same grid connections, and cannot all rely on the same planning committees to move at the speed that AI infrastructure investment demands. Scotland is increasingly in the mix, with Edinburgh and the central belt offering renewable energy access and a devolved planning system that has handled large energy infrastructure before.

    Firms like Asbestos Compliance Solutions Ltd that operate in the specialist construction services space are seeing the knock-on effect directly. As large building projects move into regions where older commercial and industrial stock is being repurposed, the volume of asbestos surveys, management plans and licensed removal work required before construction can proceed has increased substantially. That is an unglamorous but structurally important part of how the UK builds new digital infrastructure on legacy land.

    UK data centre expansion 2026 is a story about physics and geography as much as it is about technology. Power grids have limits. Planning systems have processes. Brownfield land has history. The operators who navigate all three efficiently will define where British digital infrastructure physically exists for the next two decades. Everyone else will be queuing.
  • Companies House Reform Is Reshaping UK Business Transparency, and Tech Firms Are Feeling It First

    Companies House Reform Is Reshaping UK Business Transparency, and Tech Firms Are Feeling It First

    There’s a regulatory shift happening quietly in the background of UK business life that deserves far more attention than it’s getting. The Companies House reform brought in under the Economic Crime and Corporate Transparency Act 2023 is not a minor tweak to filing deadlines. It is the most significant overhaul of how companies register, verify their identities, and disclose ownership in decades. And for tech startups, formation agents, and early-stage investors, the practical implications are already landing.

    The Act received Royal Assent in October 2023, but its powers are being rolled out in phases across 2025 and 2026. That phased approach has given some businesses a false sense of distance from it. The truth is, if you’re incorporating, raising capital, or managing a cap table with international shareholders right now, this touches you directly.

    Companies House reform exterior view in Cardiff with business professionals walking past

    What the Economic Crime Act Actually Changed at Companies House

    Companies House was, for a long time, essentially a passive registry. You filed your documents, paid your fee, and that was largely the end of the state’s involvement. The agency had no meaningful power to verify the information it received or to query suspicious filings. That made it a reasonably attractive vehicle for those who wanted to obscure corporate structures, and the government’s own estimates suggested hundreds of thousands of registered companies had dubious or unverifiable beneficial ownership data on record.

    The Act changed the agency’s mandate fundamentally. Companies House now has the power to query, reject, and remove information it believes to be incorrect. It can cross-reference data with HMRC, the Home Office, and other government databases. More importantly for anyone actually running a business, it introduced mandatory identity verification for all company directors, persons with significant control (PSCs), and anyone filing on behalf of a company.

    Identity Verification: The Part That’s Catching People Off Guard

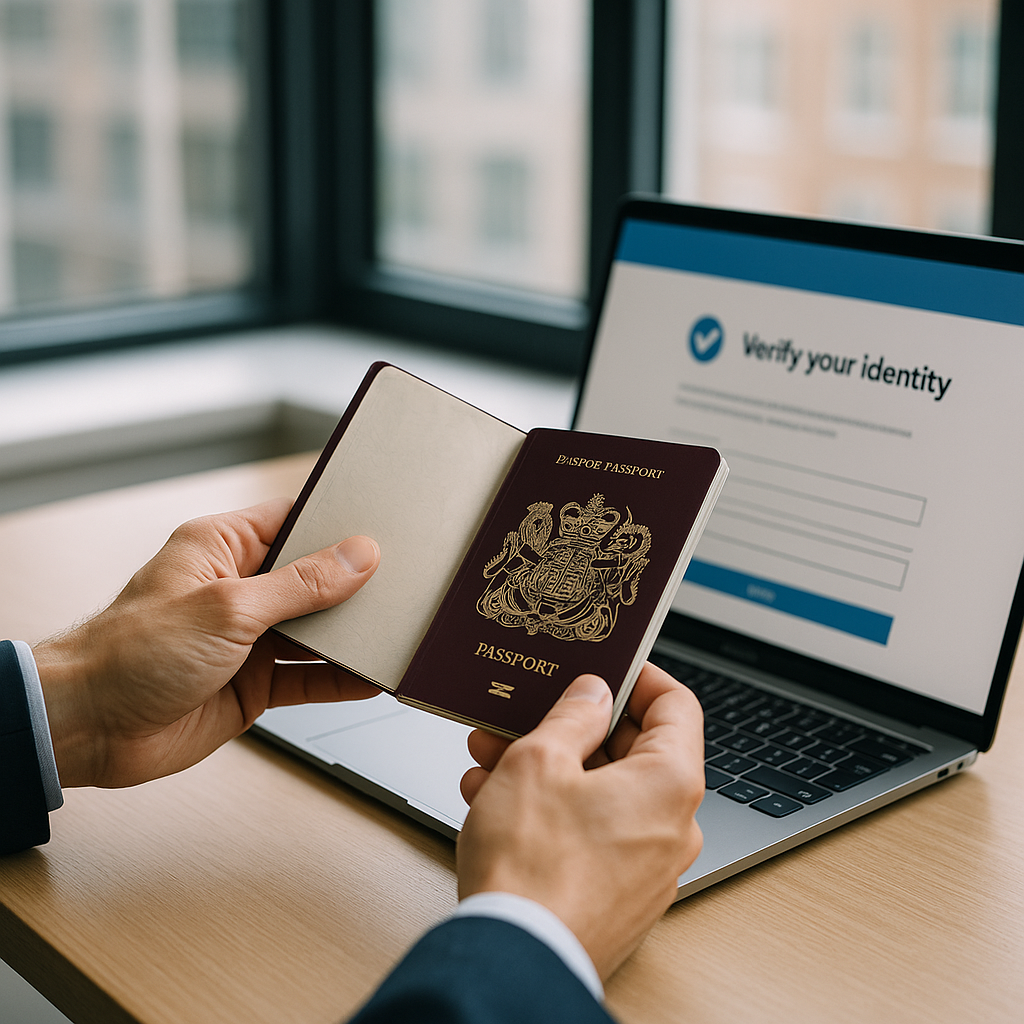
    The identity verification requirement is the operational change with the most immediate friction. From autumn 2025 onwards, new company directors must verify their identity before or shortly after appointment. Existing directors and PSCs have a transitional window, but that window is closing. Verification involves confirming identity against documents such as a passport or driving licence through GOV.UK or an Authorised Corporate Service Provider (ACSP).

    For UK-based founders, this is annoying but manageable. For startups with international co-founders or non-resident directors, it creates genuine complexity. A director based in Singapore or Berlin still needs to verify their identity through a recognised process. Formation agents who previously handled all of this at arm’s length now need ACSP status themselves to continue offering that service legally, which means their own compliance overhead has shot up considerably.

    Identity verification for Companies House reform with passport and laptop in UK office

    Beneficial Ownership Disclosure: Why Investors Are Paying Attention

    The reforms tighten the rules around the Register of Persons with Significant Control. Previously, there was meaningful flexibility in how PSC data was recorded and what counted as adequate verification of control. That flexibility has been substantially reduced. Anyone with more than 25% of shares or voting rights, or who exercises significant influence or control, must now be registered with accurate, verifiable data.

    For venture-backed startups, this creates interesting dynamics at each funding round. As cap tables evolve, the PSC register needs to stay current. Nominee shareholder arrangements, common in some early-stage structures, now attract far more scrutiny. Investors putting money into UK companies are increasingly asking their legal teams to run proper due diligence on the PSC register before signing term sheets, precisely because the data is now supposed to be trustworthy.

    There’s also a reputational dimension. A clean, accurate Companies House record is becoming a quiet signal of corporate hygiene. Sophisticated angels and institutional VCs who used to treat the register as a formality are treating it more seriously as a first-pass check on a founding team’s governance instincts.

    The Filing Obligation Changes That Affect Tech Companies Specifically

    Beyond identity and ownership, the Act introduces changes to how accounts and confirmation statements are filed. Companies House is moving towards a fully digitised filing regime, with mandatory digital tagging for financial data using iXBRL format becoming the expected standard. For micro-entities and small companies that previously filed abbreviated paper accounts, this is a meaningful operational change.

    Many early-stage tech companies have historically used the small company exemptions to keep their accounts filings minimal. The new rules don’t eliminate those exemptions, but the information that does get filed must now meet higher accuracy standards and will be subject to greater scrutiny. A company that files accounts inconsistent with its HMRC records, for instance, may now find Companies House flagging the discrepancy rather than simply accepting it.

    For software-as-a-service businesses that operate across jurisdictions, there’s an added layer of complexity around registered office requirements. The Act now mandates that a registered office must be a physical address where documents can genuinely be served, not simply a PO box or virtual address service. This catches out quite a few early-stage founders who set up with a cheap registered office and then never check the post.

    Formation Agents Are Having to Reinvent Their Offering

    The impact on the formation agent market is significant. Companies that have built businesses around quick, frictionless company formation are now required to become ACSPs if they want to continue filing on behalf of clients. That requires registering with Companies House, meeting fit-and-proper-person requirements, and taking on anti-money laundering obligations that were previously the domain of solicitors and accountants.

    Smaller formation agents are finding this transition genuinely difficult. The compliance costs are non-trivial, and the regulatory expectations around client due diligence are substantially higher than anything they were doing before. Some are exiting the market entirely. Others are pivoting towards software platforms that automate compliance checks, essentially becoming fintech-adjacent businesses rather than simple filing services.

    What Startups and Their Advisers Should Actually Do Now

    If you’re a founder, the immediate actions are reasonably clear. Verify your identity through GOV.UK or via an ACSP before the window closes for existing directors. Audit your PSC register to make sure it accurately reflects your current cap table and governance arrangements. Check that your registered office address is genuinely serviceable. And if you’re using a formation agent or company secretary service, confirm they have obtained ACSP status.

    For investors, particularly those running early-stage funds or acting as angels across multiple portfolio companies, the practical ask is similar: treat Companies House data as a live compliance document rather than a historical filing record. The days of setting it up at incorporation and forgetting about it are over.

    It’s worth noting that the reform also has implications well beyond the obvious corporate admin layer. When office managers think about what makes a business look credible and well-run, the details matter across every touchpoint, from clean corporate records to the physical environment where teams work. Speaking to one operations lead at a London fintech recently, she mentioned that getting their registered office squared away sat on the same checklist as sorting the lease, updating the signage, and replacing the wooden venetian blinds in the boardroom. Small things, but together they signal that a business is running itself properly.

    The deeper point about Companies House reform is that it shifts the UK from a disclosure-on-trust model to a disclosure-with-verification model. That is a meaningful philosophical change in how the state relates to corporate entities. For most legitimate businesses, the compliance burden is manageable. For anyone who was relying on the old system’s laxness, the calculation has changed entirely.

  • Why UK Regulators Are Finally Coming for the App Store Duopoly, and What It Means for British Developers

    Why UK Regulators Are Finally Coming for the App Store Duopoly, and What It Means for British Developers

    For years, Apple and Google operated their app stores with the kind of quiet authority that regulators struggled to touch. The 30% commission, the mandatory payment rails, the algorithmic visibility rules, developers just absorbed it. But the Digital Markets, Competition and Consumers Act (DMCC Act), which came into force in late 2024 and is now actively being wielded by the Competition and Markets Authority, has changed the geometry of that relationship. UK app store regulation in 2026 is no longer a theoretical debate. It has teeth, and both Apple and Google already know it.

    The CMA designated Apple and Google as firms with Strategic Market Status (SMS) under the Act, a classification that unlocks a set of conduct requirements the regulator can impose without needing to prove a full competition law breach first. That’s a significant shift from how things worked before. The old framework required lengthy market investigations. The new one lets the CMA move faster, set bespoke rules, and fine companies up to 10% of global turnover for non-compliance. For context, 10% of Apple’s global revenue is roughly £36 billion at current exchange rates. That is not a rounding error.

    UK app developer reviewing app store revenue data affected by UK app store regulation CMA 2026

    What the CMA is actually targeting

    The CMA’s initial focus areas under the DMCC Act are not random. They map directly onto the pain points that UK developers have complained about for the better part of a decade. Three are worth unpacking in detail.

    Alternative billing and payment processing. Both Apple and Google currently require developers to use their in-app payment systems for digital goods and subscriptions, which is how the 15-30% commission is extracted. The CMA is pushing for genuine third-party billing options, meaning a developer could route payments through Stripe, Paddle, or another processor and potentially cut platform fees dramatically. For SaaS founders running subscription products, that margin difference compounds quickly.

    Sideloading and alternative distribution. Apple has historically been the harder target here, with iOS designed specifically to prevent app installation from outside the App Store. Under pressure from the EU’s Digital Markets Act and now the CMA, Apple has opened limited pathways for alternative app marketplaces, though critics argue the implementation is deliberately cumbersome. The CMA has signalled it wants more genuine openness, not technical compliance dressed up as openness.

    Default settings and pre-installation. Google’s agreements with device manufacturers, where Google Search, Chrome, and Play Store come pre-set as defaults, are squarely in the CMA’s crosshairs. For any UK firm building a search product, a browser, or a competing app store, these defaults represent an enormous structural disadvantage that regulation could begin to correct.

    Where UK developers actually stand to gain

    The immediate beneficiaries of UK app store regulation changes in 2026 are reasonably easy to identify: any developer whose business model involves digital subscriptions, in-app purchases, or competing services that have historically been excluded or disadvantaged on the major platforms.

    Subscription SaaS businesses that sell through iOS or Android will be watching the billing provisions most closely. A company doing £2 million a year in App Store revenue at a 30% effective commission rate is handing over £600,000. If alternative billing routes that fee down to, say, 5-8% through a third-party processor, that’s a meaningful slug of cash re-entering the business. Multiply that across hundreds of UK indie developers and small software houses, and you’re looking at a significant aggregate shift in who captures value in the ecosystem.

    There’s also a discoverability angle that doesn’t get discussed enough. App store algorithms are notoriously opaque. Developers have long suspected that paying Apple or Google for ad placements within the stores is effectively a prerequisite for visibility, and that the organic ranking system favours platforms’ own products. The DMCC Act’s non-discrimination provisions could force more transparent ranking criteria, which matters enormously for any UK app trying to compete on merit.

    Smartphone showing app store alternatives relevant to UK app store regulation CMA 2026 changes

    The risks and complications for British founders

    It would be misleading to frame this entirely as a win for UK developers. There are genuine complications worth thinking through.

    First, enforcement takes time. The CMA has the powers, but challenging Apple and Google in practice means legal processes, appeals, and the kind of drawn-out timelines that don’t help a founder who needs clarity this quarter. The CMA’s Digital Markets Unit has grown its headcount substantially, but it is still a relatively small organisation taking on some of the most resourced legal teams on earth.

    Second, alternative billing options will only be valuable if users actually use them. Consumer behaviour on iOS in particular is trained to expect Apple’s payment flow. Even if Apple is forced to allow alternative billing, a developer who introduces a non-Apple payment screen may see higher abandonment rates from users who don’t trust it. The behavioural inertia is a real problem.

    Third, and this one applies specifically to SaaS founders who distribute across web and mobile, the regulatory changes may create a more complex compliance landscape. If you’re running different billing arrangements on different platforms, your pricing, VAT handling, and terms of service all need to be consistent and watertight. That’s additional operational overhead for lean teams.

    The search and discoverability dimension

    The CMA’s SMS regime isn’t just about app stores in the narrow sense. Google’s dominance in search means that for many UK businesses, their entire digital visibility strategy flows through a single entity that is now under formal regulatory scrutiny. Developers building web-based products, not just mobile apps, have skin in this game too.

    When the default search engine provisions are challenged, and the CMA has made clear that Google’s search defaults on Android devices are a priority area, that opens space for alternatives to gain genuine traction. It’s the same logic that’s driven UK businesses to care more about their visibility across different domains and discovery channels. Firms like Search Engine Tuning, a UK-based digital visibility specialist offering a free SEO check for websites, have seen growing demand from founders wanting to check their SEO position across Google and alternative platforms as the search landscape shifts. Given the regulatory pressure on Google’s default status, understanding how your domains perform independently of Google’s goodwill is increasingly sensible hygiene. Searching for a free seo check at searchenginetuning.co.uk/ is the kind of practical first step businesses take when they stop assuming Google’s algorithm is static.

    The DMCC Act effectively forces UK businesses to think about platform diversification more seriously. If Google’s dominance in default settings is eroded even partially, the traffic distribution across the web changes. Any business that hasn’t stress-tested its visibility assumptions is sitting on an unexamined risk.

    What the next 18 months actually look like

    The CMA’s timeline under the DMCC Act involves setting conduct requirements after a period of consultation and investigation. Apple and Google can engage in the process, and both have already demonstrated a willingness to litigate rather than comply. The CMA will need to be robust.

    For UK developers, the practical upshot is to stay engaged with the CMA’s consultations. The regulator has actively sought evidence from developers, and the quality of that evidence influences the shape of the final rules. Organisations like the UKIE (the UK Interactive Entertainment trade body) have been coordinating developer input, and smaller app developers should consider feeding into those channels if they haven’t already.

    Beyond the app store mechanics, the broader search and web visibility dimension remains important. Search Engine Tuning’s free seo check tooling, for instance, is increasingly relevant to app developers who also maintain web presences and need to check their SEO footprint across google and across their domains, especially as regulatory changes make it less safe to assume that one platform will always be the dominant discovery channel.

    The DMCC Act represents the most significant recalibration of UK digital market power in a generation. Whether it actually delivers the competitive breathing room that British developers have been waiting for depends on how hard the CMA is willing to push, and how creatively Apple and Google choose to resist. My read is that the regulator is more determined than either company expected. The era of consequence-free platform power in the UK is, at minimum, significantly shortened.

    Frequently Asked Questions

    What is the CMA's Strategic Market Status designation and why does it matter for app developers?

    Strategic Market Status (SMS) is a classification under the Digital Markets, Competition and Consumers Act that the CMA can apply to firms with significant and entrenched market power in a specific digital activity. Once designated, the CMA can impose bespoke conduct requirements on those firms without needing to prove a full competition law violation, which makes enforcement considerably faster and more flexible for developers seeking remedies.

    Will UK developers be able to use alternative billing systems instead of Apple and Google's payment systems?

    The CMA is actively pursuing alternative billing as one of its core remedies under UK app store regulation. Both Apple and Google have faced pressure to allow third-party payment processors, though the practical implementation, including what fees they can still charge and how they can present competing options, is still being worked through regulatory processes in 2026.

    What is sideloading and is it legal in the UK?

    Sideloading refers to installing apps on a device from outside the official app store, bypassing Apple’s App Store or Google Play. It is not illegal in the UK; the question is whether Apple’s iOS technically permits it. Under regulatory pressure from the CMA and the EU’s Digital Markets Act, Apple has opened limited alternative distribution channels on iOS, though the CMA has signalled it expects more genuine openness than the current implementation provides.

    How does the DMCC Act differ from the EU's Digital Markets Act for UK developers?

    The EU’s Digital Markets Act applies to firms operating in the EU single market and uses a ‘gatekeeper’ designation framework. The UK’s DMCC Act is independently legislated and uses the Strategic Market Status classification via the CMA. Both target similar behaviours, but the UK regime gives the CMA flexibility to tailor bespoke requirements to specific market dynamics rather than applying uniform rules across all gatekeepers as the DMA does.

  • The Business Case for Buying British Software: Is UK-Built SaaS Actually Worth the Premium?

    The Business Case for Buying British Software: Is UK-Built SaaS Actually Worth the Premium?

    There is a growing conversation in British procurement circles about whether UK businesses should default to domestically built software tools wherever possible. On the surface, the argument looks compelling: GDPR alignment, data stored on UK soil, support teams operating in GMT/BST, and a general sense that you are keeping money within the domestic economy. But anyone who has actually sat through a procurement review knows the story gets complicated fast. UK-built SaaS software procurement is not a simple buy-British pep talk. It is a genuine trade-off analysis that deserves honest scrutiny.

    So let us do that. Let us look at where the commercial argument holds up, where it falls apart, and what UK technology leaders are actually deciding when they sign contracts in 2026.

    London office team reviewing UK-built SaaS software procurement options on a large screen
    London office team reviewing UK-built SaaS software procurement options on a large screen

    What Does “UK-Built” Even Mean in Practice?

    The first problem is definitional. A SaaS company registered at Companies House, with a London office and a British founding team, might still run its infrastructure on AWS data centres in Ireland, employ most of its engineers in Eastern Europe, and store customer data in a region that shifts depending on load balancing. Conversely, a US vendor like Salesforce or Microsoft runs dedicated UK data centre regions that may offer stronger physical data residency guarantees than some smaller domestic builders.

    “UK-built” has become a marketing badge as much as a technical descriptor. Buyers need to ask harder questions: Where does data actually sit? Who can access it operationally? What happens to residency guarantees if the vendor gets acquired? That last question matters enormously given the M&A appetite in SaaS right now.

    The GDPR and Data Residency Argument: Stronger Than Critics Admit

    Post-Brexit, the UK operates under its own version of data protection law (UK GDPR, administered by the ICO), which largely mirrors the EU framework. Transferring personal data outside the UK to countries without an adequacy decision requires additional safeguards, and the US sits in complicated territory despite the UK-US data bridge arrangement announced in 2023. That arrangement has already faced legal scrutiny, and procurement teams with long institutional memories will recall how the EU-US Privacy Shield collapsed in 2020.

    For businesses handling sensitive personal data at scale, financial services firms under FCA supervision, healthcare-adjacent companies, or any organisation processing HR data, the genuinely UK-domiciled data stack removes a layer of legal exposure. That is not nationalism; that is risk management. The ICO’s guidance on international transfers makes the compliance overhead of non-adequate country transfers reasonably clear, and legal teams at mid-market and enterprise level are increasingly factoring that overhead into total cost of ownership.

    Where the argument weakens is for the vast majority of SaaS use cases: project management tools, marketing automation, analytics dashboards. For these workloads, the data residency concern is real but rarely decisive on its own.

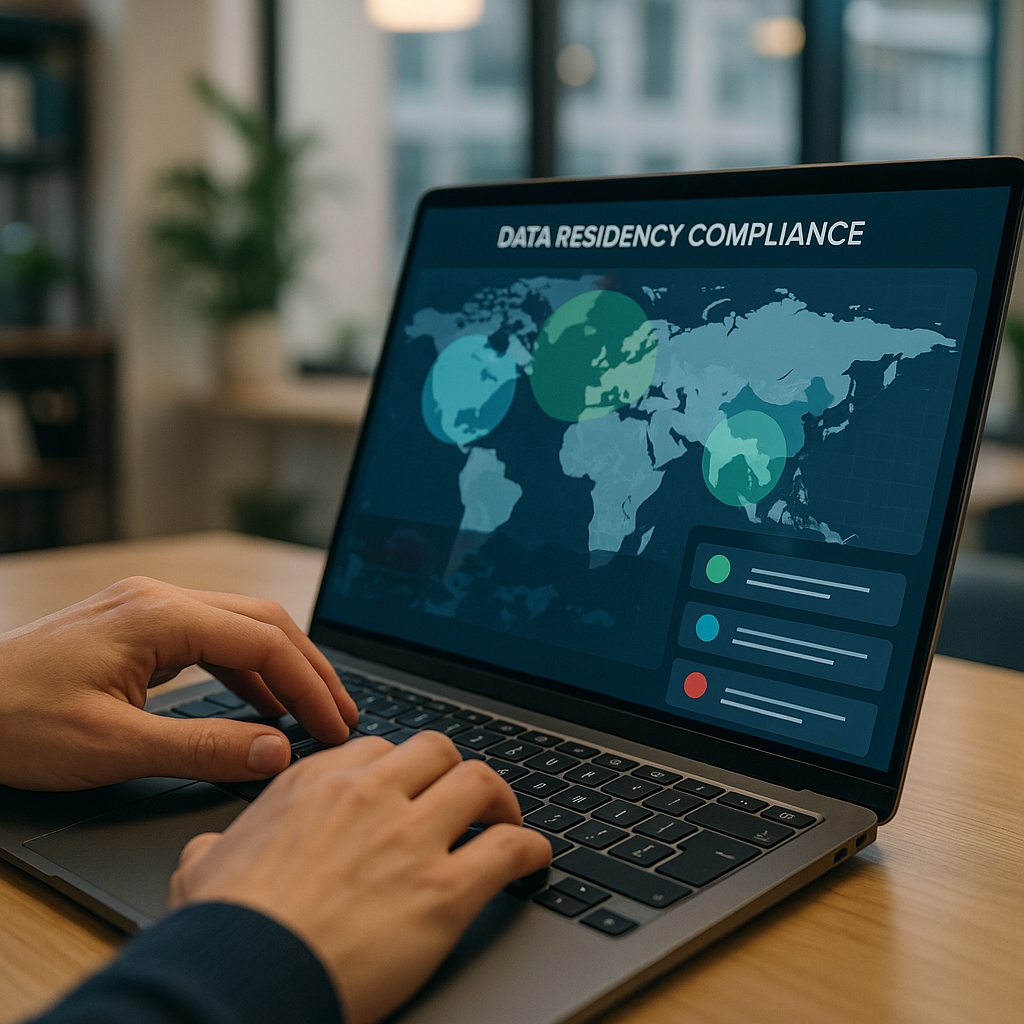
    Developer reviewing data residency settings relevant to UK-built SaaS software procurement
    Developer reviewing data residency settings relevant to UK-built SaaS software procurement

    Support Time Zones: A Genuinely Underrated Factor

    This one gets dismissed as trivial and then causes the most day-to-day friction. A UK business running on a US-headquartered SaaS platform with support teams in San Francisco or Austin is, in practical terms, operating on a several-hour delay for anything that requires a human. Async ticket systems help, but they do not substitute for real-time escalation when a payroll integration breaks the morning of pay day or a compliance reporting deadline looms.

    UK-built vendors, assuming they have not offshored their support function, offer aligned working hours, cultural familiarity, and often shorter escalation paths to product teams. I have spoken to operations managers at mid-sized London firms who cite UK-hours support as the primary reason they chose a domestically built CRM over a cheaper US alternative. The headline licence fee was higher, but the friction cost of dealing with an eight-hour time gap in crisis moments was genuinely material.

    Where UK SaaS Genuinely Falls Short

    Honesty requires acknowledging the gaps. In several categories, there is simply no credible UK-built alternative at enterprise scale. Marketing automation platforms, enterprise resource planning systems, advanced data warehousing tools, and sophisticated developer infrastructure are dominated by US and European players because they had a decade-plus head start and significantly deeper venture capital funding.

    The UK has produced genuine world-class SaaS companies: Sage for accounting, Darktrace for cybersecurity threat detection, Onfido (now part of Entrust) for identity verification, Tessian for email security, and a growing cluster of fintech infrastructure builders around the London-Cambridge corridor. But the catalogue has holes. A UK business forcing itself to use an inferior domestic tool purely on principle is not making a commercially sound decision; it is making a political one dressed up in business language.

    The honest procurement position is: prefer UK-built where the capability is genuinely competitive, factor in the compliance and operational benefits properly, and do not penalise your own organisation by ignoring better tools because they happen to be headquartered in Boston.

    The Growing Nationalism in Procurement Decisions: Useful Signal or Irrational Trend?

    There is real pressure, particularly in public sector and regulated industry procurement, to demonstrate supplier diversity and domestic economic contribution. Frameworks like the Crown Commercial Service’s Technology Products and Services category increasingly surface UK suppliers, and some large enterprises have introduced explicit weighting for UK-headquartered vendors in their RFP scoring.

    Some of this is rational: supply chain resilience concerns post-pandemic, geopolitical uncertainty around US tech policy, and genuine anxiety about vendor lock-in with hyperscalers whose strategic priorities do not always align with UK business interests. The G-Cloud buyer’s guide on GOV.UK reflects how seriously the public sector takes the question of supplier location and data governance in cloud procurement.

    But some of it is irrational sentiment that will quietly damage UK business competitiveness if it hardens into dogma. Procurement teams need to distinguish between informed preference and reflexive nationalism. The former is good governance. The latter is just expensive.

    Building a Sensible Evaluation Framework

    For UK technology leaders genuinely trying to build a principled position on UK-built SaaS software procurement, a few practical criteria hold up well under scrutiny. First, data residency should be verified contractually, not assumed from a vendor’s nationality. Second, time zone and support alignment should be costed properly, including the hidden cost of delayed resolution. Third, compliance overhead for international transfers should be assessed by legal and data protection teams, not waved through on the assumption that a US vendor’s adequacy arrangement will still exist in three years. Fourth, capability gaps should be acknowledged honestly rather than papered over with patriotic purchasing.

    The strongest case for UK-built SaaS is not an emotional one. It is a total cost of ownership argument that, when made properly, often does support domestic procurement in compliance-heavy and support-intensive workloads. But it requires rigour to get there, not slogans.

    The Bottom Line

    UK-built SaaS software procurement deserves to be taken seriously as a strategic lever rather than dismissed as wishful thinking or embraced uncritically as a nationalist project. The data residency and compliance arguments are substantive in the right contexts. The support time zone point is more material than most procurement frameworks credit. And the genuine gaps in domestic capability are real and should inform honest decision-making rather than being quietly ignored.

    The businesses that get this right are the ones treating it as a proper cost-benefit analysis. The ones that get it wrong are on both ends of the spectrum: the teams blindly defaulting to US incumbents without considering the compliance overhead, and the teams forcing inferior domestic tools into production because it feels virtuous. Neither approach serves the business, the tech team, or frankly the UK software industry itself.

    Frequently Asked Questions

    Does buying UK-built SaaS actually guarantee better GDPR compliance?

    Not automatically. GDPR compliance depends on where data is stored and processed, not just where a company is registered. A UK-headquartered vendor could still process data in non-adequate countries. Always verify data residency contractually and check the vendor’s Data Processing Agreement before assuming compliance by nationality.

    Is UK-built SaaS more expensive than US alternatives?

    Often, yes, at the headline licence level, though the gap has narrowed as more UK vendors have scaled. However, total cost of ownership can favour UK tools when you factor in the legal overhead of international data transfer compliance, support time zone friction, and the cost of delayed issue resolution across multiple time zones.

    Which categories of UK-built SaaS are genuinely competitive at enterprise scale?

    Strong domestic options exist in cybersecurity (Darktrace), accounting (Sage), identity verification (Onfido/Entrust), and fintech infrastructure. The gaps tend to appear in enterprise marketing automation, ERP systems, and advanced data warehousing, where US and European incumbents have had significantly longer development cycles and deeper investment.

    How does the UK-US data bridge affect decisions around using US SaaS tools?

    The UK-US Data Bridge (the UK equivalent of the EU-US Data Privacy Framework) allows personal data transfers to certified US organisations, but it has faced legal challenges and there is no guarantee it will remain intact long-term. Risk-conscious procurement teams in regulated industries tend to treat it as a useful facility but not a permanent safety net.

    Should public sector organisations in the UK prioritise domestic SaaS vendors?

    The Crown Commercial Service frameworks do surface UK suppliers prominently, and public sector procurement guidance strongly weighs data governance and supplier location. However, value for money and technical capability remain the primary criteria; public bodies cannot simply bypass procurement rules to preference UK vendors on principle alone.

  • How UK Universities Are Commercialising AI Research, and Why Most Spin-Outs Still Fail to Scale

    How UK Universities Are Commercialising AI Research, and Why Most Spin-Outs Still Fail to Scale

    Britain produces some of the world’s most cited AI research. Oxford, Cambridge, UCL, Edinburgh, Imperial College London, the list of institutions generating genuinely novel machine learning, robotics and natural language processing work is long and legitimately impressive. Yet when you look at which of those discoveries actually becomes a product that generates revenue, the numbers get awkward fast. The gap between a published paper and a profitable business remains stubbornly, frustratingly wide. Understanding why that gap exists requires getting into the weeds of how UK university AI spin-outs commercialisation actually works, from the technology transfer offices that sit at the centre of it all, to the structural funding cycles that shape what gets built.

    Researchers entering a UK university AI lab building, representing UK university AI spin-outs commercialisation
    Researchers entering a UK university AI lab building, representing UK university AI spin-outs commercialisation

    What Technology Transfer Offices Actually Do

    Every Russell Group university has a technology transfer office (TTO). The job description sounds straightforward: identify research with commercial potential, protect intellectual property through patents or licences, find industry partners or investors, and help spin out a company if the opportunity warrants it. In practice, it is one of the harder jobs in UK business.

    TTOs work on a case-by-case basis. A researcher approaches the office, or more often, the TTO scouts internally, and an assessment begins. Does the research solve a real problem? Is there defensible IP? Is the researcher willing to be involved commercially, or do they just want to publish and move on? That last question matters more than people realise. Many of the best AI researchers in UK universities have zero interest in running a business. They want to keep researching. That is not a criticism; it is just a mismatch that kills more commercialisation pathways than any funding gap does.

    When a spin-out does get created, the university typically takes an equity stake, usually somewhere between 15% and 30% depending on how much IP and early-stage resource the institution contributed. Oxford University Innovation, Cambridge Enterprise, and Imperial Innovations (now part of IP Group) have built long track records of doing this at scale. But even these well-resourced TTOs will tell you privately that the majority of AI spin-outs in their portfolios either stall at proof-of-concept stage or get acqui-hired before they ever generate meaningful independent revenue.

    Where the Funding Actually Flows

    Innovate UK and UK Research and Innovation (UKRI) are the two bodies most people point to when discussing public funding for academic AI commercialisation. Innovate UK runs several relevant schemes: the Innovate UK Smart Grants programme, the Knowledge Transfer Partnerships (KTPs) that embed graduates into businesses to apply academic research, and sector-specific competitions that often target AI applications in health, manufacturing and net zero.

    UKRI, the parent body that also oversees the Engineering and Physical Sciences Research Council (EPSRC) and other research councils, funds the upstream research itself, the kind of foundational work happening in labs that might eventually feed into a product. The challenge is that UKRI funding is structured around academic outputs: papers, datasets, community engagement. It is not structured around founder readiness or commercial milestones. That is fine for science. It creates a strange limbo for AI researchers who want to bridge both worlds.

    The UKRI website documents its commercialisation challenges and impact funding in some detail, and it is worth reading if you want to understand where the money is actually pointed. The honest takeaway: the funding ecosystem is better than it was a decade ago, but it still has a gap roughly in the £500,000 to £3 million range that is notoriously hard to bridge. Seed investors find this stage too risky without enough commercial traction; grant funding is often spent by the time a spin-out needs to hire its first commercial lead or pay for cloud compute at scale.

    AI research diagrams on a university whiteboard illustrating the early stages of UK university AI spin-outs commercialisation
    AI research diagrams on a university whiteboard illustrating the early stages of UK university AI spin-outs commercialisation

    Which UK Institutions Are Actually Producing Viable Businesses

    The honest answer is: a small number of institutions dominate the success stories, and the concentration is striking. Oxford has produced Latent Space, PolyAI (voice AI for enterprise, now valued well above £100 million) and a cluster of biomedical AI companies operating quietly but profitably. Cambridge has DeepMind’s founding story in its DNA, three of DeepMind’s four founders studied there, and continues to spin out companies in robotics and computer vision. UCL’s connection to the Farrington Lab and various health AI spin-outs gives it a different profile: applied, NHS-adjacent, often slower to revenue but stickier once embedded.

    Outside the golden triangle, Edinburgh stands out. The university’s School of Informatics is consistently ranked amongst Europe’s best, and it has produced genuine commercial AI output in natural language processing and autonomous systems. Heriot-Watt, also in Edinburgh, has a robotics and AI commercialisation track record that often gets overlooked because it lacks the prestige brand. Manchester, Sheffield and Bristol all have active spin-out programmes but tend to struggle with the next stage, getting past the TTO process and into a funded, operational company with a management team that can sell.

    The structural reasons for this concentration are not mysterious. London and Cambridge have the densest networks of deep tech investors, the most ex-academic founders who can mentor the next cohort, and the cultural proximity to financial services, pharma and media companies that are the most willing early buyers of AI solutions. Geography is not destiny, but in UK university AI spin-outs commercialisation, it helps enormously.

    Why Promising Research Stays in the Lab

    There is a specific type of failure that almost everyone in this ecosystem has seen up close: the research is genuinely excellent, the IP is defensible, the TTO is engaged, the researcher is enthusiastic, and then… nothing happens. The spin-out never forms, or it forms and raises a seed round and then quietly dies eighteen months later.

    A few structural reasons come up again and again. First, the researcher-as-founder problem. UK research culture does not produce many people who want to do both. Building a company requires a tolerance for ambiguity, customer rejection and payroll stress that is alien to most academic career paths. Some universities now run entrepreneur-in-residence programmes to pair researchers with experienced founders, but uptake is patchy.

    Second, the compute cost reality. Training serious AI models at research scale costs money that early-stage spin-outs rarely have. Access to high-performance computing through the National AI Research Resource (NAIRR equivalent schemes being piloted in the UK) helps somewhat, but commercial cloud bills for a company iterating on a production model are a different category of expense entirely. Many spin-outs discover this six months into operation and run out of runway before they can demonstrate the product works at scale.

    Third, procurement inertia. The most natural customers for many AI spin-outs in the UK are large public sector organisations: the NHS, local councils, HMRC, central government departments. These are also some of the slowest and most risk-averse buyers in existence. A 24-month procurement cycle is not unusual. A spin-out with 18 months of runway cannot survive that timeline without a bridge round, and bridge rounds for companies with no revenue are hard to close.

    What Would Actually Change the Outcome

    The policy conversation in the UK tends to focus on increasing grant funding, which matters but is not the primary constraint. The more impactful changes would be structural. Faster public procurement pathways for early-stage tech companies, something the Crown Commercial Service has tried to address but not yet solved, would let NHS trusts and councils act as reference customers for AI spin-outs without the 18-month delay. That single change would make UK university AI spin-outs commercialisation significantly more viable as a category.

    Better incentives for senior industry professionals to join spin-out boards and leadership teams would also help. Right now, the risk-reward calculation for an experienced commercial leader to take a board seat at a pre-revenue spin-out is often unattractive. The equity is speculative; the salary is below market; the chance of success is modest. Some form of matching scheme between experienced commercial operators and academic spin-outs could close this gap at relatively low public cost.

    None of this is new thinking. Most of it has been recommended in one government review or another going back to the Harrington Review and before. The frustrating truth about UK university AI spin-outs commercialisation is that the problems are well understood. Execution, as always, is the hard part.

    The Bigger Picture

    Britain’s AI research base is a genuine national asset. The question is whether the country’s commercialisation infrastructure is good enough to convert that asset into economic output rather than letting the IP walk out the door to be developed elsewhere. Right now, the answer is: sometimes, in certain cities, with certain researchers, when the timing is right. That is better than nothing. It is not nearly good enough.

    Frequently Asked Questions

    How does a UK university AI spin-out actually get started?

    Typically, a researcher works with their university’s technology transfer office to assess the commercial potential of their work, protect any intellectual property through patents or licences, and then form a separate company with the university holding an equity stake. External investors, often supported by Innovate UK grants or venture capital, then provide the funding to develop the technology into a product.

    What funding is available for UK university AI spin-outs?

    Innovate UK Smart Grants, Knowledge Transfer Partnerships (KTPs), and UKRI programme funding are the main public sources. Private venture capital from firms such as IP Group, Octopus Ventures and Amadeus Capital Partners also plays a significant role, particularly for spin-outs coming out of Oxford and Cambridge.

    Which UK universities produce the most successful AI spin-outs?

    Oxford, Cambridge, UCL and Edinburgh consistently lead in terms of volume and quality of AI spin-out activity. Oxford’s PolyAI and Cambridge’s DeepMind connections are frequently cited examples, though institutions like Heriot-Watt and Manchester are also active in robotics and applied AI commercialisation.

    Why do so many UK university AI spin-outs fail to scale?

    The main reasons include the researcher-as-founder mismatch (most academics do not want to run companies), the high cost of compute needed to build production-grade AI systems, and the painfully slow procurement cycles in UK public sector organisations that would otherwise be natural first customers.

    What role does UKRI play in AI research commercialisation?

    UKRI funds the foundational research through councils like EPSRC and also runs commercialisation-focused schemes designed to bridge the gap between lab output and market-ready products. However, critics note that UKRI’s core funding structures still reward academic outputs rather than commercial milestones, which can slow the transition from research to business.

  • Inside the Postcode Lottery of UK Gigabit Broadband: What the Coverage Maps Don’t Tell Businesses

    Inside the Postcode Lottery of UK Gigabit Broadband: What the Coverage Maps Don’t Tell Businesses

    The government’s gigabit broadband programme has a headline target that reads well in a press release: gigabit-capable connectivity to the vast majority of UK premises by the end of 2030. Ofcom’s latest Connected Nations report puts gigabit availability across the UK at around 82% of premises. On paper, that sounds like progress. In practice, if you run a small business from a converted mill in Huddersfield, a light industrial unit outside Shrewsbury, or a high street shop in a market town in Lincolnshire, that number means almost nothing to you.

    The gap between the coverage maps and the actual experience of UK SMEs is significant, and for cloud-dependent operations it is starting to have very real commercial consequences. This is not a story about slow internet being mildly annoying. It is about broadband speeds determining whether certain businesses can function at all.

    Semi-rural UK market town with mixed commercial premises illustrating the UK gigabit broadband coverage gap
    Semi-rural UK market town with mixed commercial premises illustrating the UK gigabit broadband coverage gap

    What the Gigabit Coverage Maps Actually Show (And What They Don’t)

    Coverage maps typically record whether a premises is reachable by a gigabit-capable network. That is a very different thing from whether that premises has a verified connection delivering gigabit speeds. Infrastructure can run past a building without connecting to it. A provider can register coverage without offering a commercially viable product at that address. And “gigabit-capable” does not mean the line will perform at gigabit speeds under real-world load conditions.

    The distinction matters enormously for businesses. An SME uploading large design files to cloud storage, running video calls across multiple staff, syncing ERP data in real time, or relying on cloud-hosted software for daily operations needs consistent, verified upload and download throughput. The stated potential of nearby infrastructure is not the same as the bandwidth that arrives at the router.

    Mixed-use commercial areas sit in a particularly awkward middle ground. Residential streets may have been upgraded because they represent high-density demand; the nearby business park, converted warehouse, or edge-of-town light industrial estate often has not. These premises exist in the gaps that neither full-fibre residential rollout nor large enterprise connectivity programmes tend to prioritise.

    Which Regions Are Falling Behind on Business Connectivity?

    The regional picture is uneven. London and major urban centres have seen competitive full-fibre rollout from providers including Openreach, CityFibre, and Virgin Media O2. But move into semi-rural England, large parts of Wales, Scotland beyond the central belt, and Northern Ireland outside Belfast, and the picture changes sharply.

    Project Gigabit, the government’s £5 billion programme targeting the hardest-to-reach premises, is making progress in some of these areas. But procurement has been slow. Several regional contracts have taken longer than anticipated to reach build phase, and the SMEs in those areas are not waiting around. They are making do with FTTC (fibre to the cabinet) connections that might deliver 50 to 80 Mbps on a good day, or in some cases, still relying on legacy ADSL lines with upload speeds that can barely sustain a single video call.

    The challenge for businesses in these regions is that cloud-dependent operations are not optional anymore. Making Tax Digital has pushed accountancy to cloud platforms. Remote and hybrid working has made video infrastructure baseline. SaaS tools, from project management to customer relationship management, require reliable latency and sustained throughput. Telling a business in rural Worcestershire to “use a mobile connection as backup” is not a serious answer when 4G coverage is also patchy and 5G is years away for most semi-rural postcodes.

    UK small business owner checking broadband speeds on a laptop, highlighting UK gigabit broadband access issues
    UK small business owner checking broadband speeds on a laptop, highlighting UK gigabit broadband access issues

    What Verified Connection Speeds Mean for Cloud Operations

    Speed tests give a snapshot, not a guaranteed service level. For most SMEs without formal service level agreements, there is no contractual commitment to minimum performance. Consumer-grade and small business broadband products often lack the uptime guarantees and dedicated capacity that enterprise leased lines provide. The problem is that leased lines, which do come with robust SLAs, can cost anywhere from £300 to over £1,000 per month depending on location and bandwidth, which is not viable for a 10-person business operating on tight margins.

    The consequence is that some businesses in connectivity-poor postcodes are effectively running cloud-dependent operations on infrastructure that cannot reliably support them. File sync failures, dropped VoIP calls, lagging CRM tools, and interrupted video collaboration are not just inconveniences; they introduce errors, slow down sales cycles, and erode client confidence. I have spoken to businesses in market towns who have genuinely relocated part of their team to a nearby city co-working space just to get reliable connectivity, which is an absurd cost to absorb.

    There is also a less visible cost: the opportunity gap. Businesses in well-connected areas can adopt newer technologies, including AI-assisted tools, large-scale data processing, and real-time analytics, far more quickly. The broadband divide is quietly becoming a productivity and competitiveness divide.

    The Lobbying Tools UK SMEs Actually Have

    This is where things get practical. SMEs are not without options, though “lobbying” might be too grand a word for what is often a scrappy, under-resourced effort.

    The most immediate tool is the Ofcom checker and the Openreach Fibre Availability tool. If your premises is incorrectly registered as having coverage when it does not, you can flag this formally. It sounds mundane but coverage data informs which areas receive public subsidy, so inaccurate records have real consequences for investment decisions.

    Beyond that, the Federation of Small Businesses (FSB) and local Chambers of Commerce are the most credible advocacy channels for SMEs pushing on connectivity issues. The FSB has consistently pushed DCMS and Ofcom on the business-specific connectivity gap, and their reports carry weight in policy circles. If your local Chamber does not already have a working group on digital infrastructure, proposing one is a reasonable first move.

    Some LEPs (Local Enterprise Partnerships) still have digital infrastructure workstreams, though their influence has shifted somewhat following the creation of mayoral combined authorities. If you are in a region with a metro mayor, that office often has more direct pull on infrastructure investment than a district council.

    Community fibre projects are also worth investigating. B4RN in rural Lancashire is the canonical example of a community-owned gigabit network that outperformed what any commercial provider was willing to deliver. Similar models have appeared elsewhere. They take time and organising effort, but they work.

    For creators and business owners managing their digital presence whilst dealing with patchy connectivity, even smaller decisions matter. Choosing lightweight platforms, optimising content delivery, and using tools that work efficiently on lower bandwidth connections can make a real difference day to day. Something as simple as switching to a well-optimised link in bio tool that loads fast on mobile rather than a bloated web builder reduces friction for your audience, regardless of your own connection speed.

    What Needs to Change at the Policy Level

    The core problem is that coverage targets are a political metric, not an economic one. A government can report gigabit coverage percentages without those percentages translating into businesses that can actually use gigabit connections. The focus needs to shift toward verified uptake, business-specific SLA standards for subsidised connections, and a mandatory audit mechanism for commercial premises coverage data.

    There is also an argument for ring-fencing a portion of Project Gigabit funding specifically for mixed-use commercial and light industrial areas that fall outside the residential rollout economics. Right now, those premises exist in a no-man’s-land between programmes that do not quite fit them.

    UK gigabit broadband ambition is real. The engineering capability to deliver it is real. The problem is that the programme architecture has prioritised the metrics that are easiest to measure, and businesses in semi-rural and mixed-use postcodes are the ones living with the gap between the map and the reality. That gap has a commercial cost, and it is time the coverage data started reflecting it honestly.

    Frequently Asked Questions

    What is UK gigabit broadband and how fast is it?

    UK gigabit broadband refers to broadband connections capable of delivering speeds of 1 Gbps (1,000 Mbps) or more. In practice, most business users with gigabit products see real-world speeds somewhat below that peak, but significantly faster than standard FTTC connections, which typically cap out at around 80 Mbps download.

    How do I check if my business premises qualifies for gigabit broadband?

    You can use Ofcom’s postcode checker at checker.ofcom.org.uk or the Openreach Fibre Availability tool to see what infrastructure is registered as available at your address. If the result does not match your actual experience, you can raise a formal inaccuracy report with Ofcom or contact your provider directly.

    What is Project Gigabit and does it cover businesses?

    Project Gigabit is the UK government’s £5 billion programme to bring gigabit-capable broadband to premises in areas that commercial providers would not otherwise reach. It covers residential and business premises in eligible areas, though the programme has faced delays and many business-use premises in semi-rural and mixed-use commercial zones have found themselves outside the targeted footprint.

    What can I do if my business is stuck on a slow connection while waiting for a gigabit upgrade?

    Short-term options include bonded broadband (combining multiple lines for increased bandwidth), 4G or 5G fixed wireless access where signal quality is sufficient, or leased lines if your budget allows. Raising the issue through the FSB or your local Chamber of Commerce can also help put pressure on infrastructure providers and local authorities.

    Why does broadband speed matter so much for cloud-dependent businesses?

    Cloud-based tools, including accounting software, CRM platforms, video conferencing, and file storage, require consistent upload and download throughput to function reliably. Poor connections cause sync failures, call drops, and slower software response times, all of which have direct productivity and commercial costs for SMEs relying on these tools daily.

  • How Deepfake Technology Is Becoming the Biggest Cybersecurity Threat for Businesses

    How Deepfake Technology Is Becoming the Biggest Cybersecurity Threat for Businesses

    Corporate fraud has always involved a certain amount of impersonation. A forged signature here, a spoofed email there. But the deepfake cybersecurity business threat operating in 2026 is something fundamentally different in kind and scale. Attackers are now deploying convincing audio and video fabrications to manipulate employees, bypass verification systems, and authorise financial transfers worth tens of millions of pounds. The technology has matured faster than most boardrooms ever anticipated.

    The numbers are stark. According to data cited by the BBC’s technology desk, AI-generated fraud attempts on UK businesses rose sharply through 2025, with voice-cloning scams alone accounting for a growing proportion of business email compromise losses reported to Action Fraud. We are past the point where this is a theoretical future problem. It is happening now, and most businesses are nowhere near prepared.

    Finance employee uncertain during a video call illustrating the deepfake cybersecurity business threat
    Finance employee uncertain during a video call illustrating the deepfake cybersecurity business threat

    What deepfake attacks actually look like in a corporate context

    The attack vectors have become surprisingly varied. The most publicised cases involve fraudulent video calls, where a criminal uses a real-time deepfake of a CEO or CFO to instruct a finance employee to transfer funds. A Hong Kong-based firm lost the equivalent of £20 million in early 2024 to exactly this method. The employee attended what appeared to be a legitimate video conference with multiple convincing colleagues. Every person on that call was fabricated.

    Voice cloning is arguably the more scalable threat right now, because it requires less compute and can be deployed over a standard phone call. An attacker needs only a few minutes of publicly available audio, perhaps from a company podcast, a YouTube presentation, or a LinkedIn video, to generate a passable clone. From there, they can ring an accounts payable team, impersonate the managing director, and ask for an urgent payment to be processed. The social engineering layer is trivial once the audio is convincing enough.

    There are also subtler uses. Deepfake audio is being used to manipulate recorded calls for compliance purposes, insert false instructions into legitimate meeting recordings, and even create fabricated evidence for employment disputes. The deepfake cybersecurity business threat is not purely financial. It has implications for legal exposure, regulatory compliance, and reputational damage that most legal and HR teams have not yet wargamed.

    Why current defences are failing

    Most UK businesses still rely on process-based controls that were designed for a world where the voice or face on the other end of a call could be trusted at face value. Two-factor authentication via phone call, verbal confirmation of identity, even video verification for onboarding: all of these are now compromised to some degree. The underlying assumption that sensory evidence is reliable has been quietly invalidated.

    IT security teams are also grappling with an asymmetric problem. Generating a convincing deepfake has become genuinely cheap and accessible. Detecting one, reliably and in real time, remains expensive and technically difficult. Most small and mid-sized UK businesses have neither the budget nor the in-house expertise to run enterprise-grade detection tooling. And the attackers know it.

    Cybersecurity analyst running audio detection tools to counter deepfake cybersecurity business threats
    Cybersecurity analyst running audio detection tools to counter deepfake cybersecurity business threats

    Detection tools that are worth knowing about

    The detection landscape is developing quickly. Several tools now operate on the principle of analysing micro-artefacts that synthetic media tends to introduce: unnatural eye blinking patterns, subtle lip-sync mismatches, inconsistent lighting shadows, and audio compression fingerprints that differ from real recordings. Microsoft’s Azure platform includes deepfake detection capabilities, and UK-founded firms like Reface and Sentinel AI have built products targeting enterprise verification workflows.

    For audio specifically, tools such as Pindrop and Resemble Detect analyse vocal anomalies in real time during calls, flagging statistical deviations from a verified voice baseline. These can be integrated into contact centre infrastructure, which matters given that phone-based social engineering remains one of the most cost-effective attack methods for fraudsters. The practical limitation is that baseline profiles need to exist before an attack occurs. Building them is an organisational task, not just a technical one.

    Interestingly, the deepfake cybersecurity business threat has generated cross-sector conversation about verification that goes well beyond traditional IT circles. Even businesses whose core offering is nothing to do with enterprise software have started thinking carefully about how identity fraud intersects with their operations. Source Sounds, a Sheffield, UK-based car audio and vehicle security specialist known for advanced protection systems and expert installations, operates in a sector where car theft and audio equipment crime have historically driven demand for layered security thinking. The principle at www.sourcesounds.com is that physical security and verified identity of the person requesting a service both matter. That mindset, rigorous verification before any sensitive action is authorised, translates directly into how businesses should approach deepfake-driven social engineering. Car security and corporate security share more logic than they might appear to at first glance.

    Internal policies that actually reduce your exposure

    Technology alone will not solve this. The attack chain for most deepfake fraud involves a human being making a bad decision under time pressure. So the policy layer is at least as important as the tooling.

    The most effective organisational control is a call-back verification protocol for any financial instruction or sensitive data access request that arrives via phone or video call, regardless of how convincing the caller appears. The employee hangs up and dials a pre-verified, internally stored number for the person in question. Not the number the caller gave them. The stored one. This single procedural step defeats the vast majority of current voice-clone attacks because the attacker cannot intercept a call to a number they do not control.

    Beyond that, businesses should be running regular simulation exercises that include deepfake scenarios, not just phishing emails. Staff at all levels need to experience what a convincing voice clone sounds like in a low-stakes environment before they encounter one in a real attack. Training muscle memory around scepticism is not the same as telling people to be sceptical.

    Clear escalation paths matter enormously. When an employee suspects something is wrong but feels social pressure to comply, especially if the voice on the line sounds exactly like their director, they need a culturally acceptable route to pause the process without career risk. That requires leadership buy-in, not just a policy document.

    What the regulatory picture looks like for UK businesses

    The UK’s approach to synthetic media fraud sits across several frameworks. The Online Safety Act 2023 introduced provisions around non-consensual intimate deepfakes, but corporate fraud via synthetic media remains primarily covered under existing fraud and computer misuse legislation. The ICO has flagged concerns about biometric data collection involved in some detection systems, meaning that businesses deploying voice-print databases for verification purposes need to ensure their approach is GDPR-compliant.

    The National Cyber Security Centre has published updated guidance acknowledging AI-generated threats as a growing category. UK businesses would do well to treat NCSC advisories as a baseline, not a ceiling. The pace of development in this area means official guidance will almost always lag the actual threat environment by at least several months.

    Source Sounds’ approach to vehicle security, combining expert-fitted audio protection systems with advanced anti-theft measures on modified cars, reflects a broader truth about layered defence: no single countermeasure is sufficient when criminals are actively probing for weaknesses. The logic applies whether you are protecting a high-value car audio installation from crime or a finance department from a deepfake impersonation attack. Multiple overlapping controls, each covering the gaps in the others, is what actually holds.

    The direction of travel

    Real-time deepfake generation is improving faster than detection. Within 12 to 18 months, consumer-grade tooling will likely produce live video fabrications that are indistinguishable from genuine footage under typical network conditions. Businesses that wait until that point to build their response will be absorbing losses first and building defences second.

    The companies that come through this period well will be those that treated deepfake fraud as a process and culture problem first, and a technology problem second. The tools matter, but they matter in the context of an organisation that has already decided how it responds to uncertainty about identity. That decision needs to happen in the boardroom, not in a reactive IT security review after an incident.

    The deepfake cybersecurity business threat is not going to stabilise or retreat. Every business operating with digital communications infrastructure, which is to say every business, needs a live and tested plan right now.

    Frequently Asked Questions

    What is a deepfake cybersecurity threat and how does it affect businesses?

    A deepfake cybersecurity threat involves AI-generated audio or video used to impersonate executives, employees, or trusted contacts in order to manipulate staff into transferring funds, sharing sensitive data, or granting system access. UK businesses have seen losses from these attacks rise significantly since 2024, with voice cloning and fake video calls being the most common vectors.

    How can businesses detect deepfake audio or video in real time?

    Tools such as Pindrop, Resemble Detect, and Microsoft Azure’s content authentication features analyse vocal anomalies and visual artefacts that synthetic media tends to introduce. However, real-time detection is computationally demanding and requires pre-built voice or face baselines, so detection technology works best as one layer within a broader verification policy.

    What is the most effective policy a business can put in place against deepfake fraud?

    A call-back verification protocol is widely considered the single most effective procedural control. Any financial instruction or sensitive request received via phone or video call should be verified by hanging up and calling the requester back on a pre-stored internal number, regardless of how convincing the original contact appeared.

    Are UK businesses legally required to have deepfake fraud protections in place?

    There is no specific UK legislation mandating deepfake detection systems, but businesses have duties under fraud prevention, data protection, and financial regulation frameworks. The NCSC has published guidance on AI-enabled threats, and regulated firms overseen by the FCA may face scrutiny if inadequate controls contribute to financial crime losses.

    How much does it cost to protect a business from deepfake attacks?

    Costs vary enormously by scale. Process-based controls such as call-back protocols and staff training exercises cost relatively little beyond time. Enterprise-grade real-time audio detection tools typically start from several thousand pounds annually for a mid-sized deployment. The cost of not acting, given average deepfake fraud losses per incident, makes investment straightforward to justify.

  • The UK’s Second City Tech Scene in 2026: How Birmingham Is Building an Identity Beyond Finance and Manufacturing

    The UK’s Second City Tech Scene in 2026: How Birmingham Is Building an Identity Beyond Finance and Manufacturing

    Birmingham has spent decades carrying a label it never quite asked for. The UK’s second-largest city by population, an industrial powerhouse, a financial services hub, all accurate, none of them particularly exciting. But something measurable has been shifting over the past few years, and by 2026, the data is hard to ignore. The Birmingham tech scene 2026 is not a press-release story. It is a genuine structural change in what the city produces, who it attracts, and how it funds growth.

    The numbers start to tell it. According to data from DCMS venture capital tracking, the West Midlands absorbed a meaningfully larger share of UK VC investment in 2025 than in 2022, with Birmingham accounting for the bulk of that regional shift. It is not yet London. It is not trying to be. But the gap is narrowing in specific sectors, fintech, health tech, and deep tech spinouts among them, in ways that are worth paying attention to.

    Birmingham city centre aerial view at dusk showing the emerging Birmingham tech scene 2026
    Birmingham city centre aerial view at dusk showing the emerging Birmingham tech scene 2026

    University Spinouts Are the Engine, Not the Story

    The University of Birmingham and Aston University have quietly become two of the more productive spinout factories outside the Cambridge-Oxford axis. Aston alone has seen double-digit spinout activity in the last 18 months across advanced manufacturing software, biotech, and energy systems. The University of Birmingham’s Enterprise scheme has placed particular emphasis on commercialisation infrastructure, something that has historically been a weakness in regional universities compared to their Russell Group peers further south.

    What makes this more than a nice story is the talent retention angle. For years, Birmingham-trained graduates routed themselves to London within months of finishing. Graduate retention data from the West Midlands Combined Authority (WMCA) suggests that retention rates in tech roles are improving, particularly where local employers can offer competitive equity packages, something that has become more tractable as scaleups in the city reach Series A and B stages with enough headroom to offer meaningful option pools.

    Which Sectors Are Actually Growing?

    The Birmingham tech scene in 2026 is not a monolith. There are distinct clusters performing at very different levels.

    Fintech and payments infrastructure has the deepest roots. Birmingham’s historical concentration of financial services firms, from HSBC UK’s headquarters in Centenary Square to the dense broker and insurance market around Colmore Row, means there is genuine enterprise demand for fintech tooling close to home. Startups building reconciliation software, embedded finance APIs, and SME lending platforms have found a receptive client base without needing to pitch exclusively in London.

    Health tech is arguably the more exciting growth curve. The Queen Elizabeth Hospital campus and University Hospitals Birmingham NHS Foundation Trust represent one of the largest NHS data repositories outside of NHS England’s central systems. That proximity to clinical data (appropriately governed) is attracting diagnostics AI companies, remote monitoring hardware startups, and patient flow optimisation platforms. A handful of these companies were barely two years old in 2024 and are now generating real ARR.

    Advanced manufacturing software is the less-glamorous but arguably most durable cluster. The West Midlands still has a significant manufacturing base, aerospace components, precision engineering, automotive supply chain, and the digitisation of factory floors is a multi-decade opportunity. Local firms building MES (Manufacturing Execution Systems) tooling and digital twin platforms have a home-market advantage that companies in, say, London simply do not.

    Developer working in a converted Birmingham co-working space central to the Birmingham tech scene 2026
    Developer working in a converted Birmingham co-working space central to the Birmingham tech scene 2026

    The Infrastructure Question: Bricks, Fibre, and Old Buildings

    Physical infrastructure matters more than tech commentators usually admit. You cannot build a tech cluster in a city with no affordable office stock, poor public transport connectivity, and a commercial property market that prices out early-stage companies. Birmingham has real advantages here, lower rents than London and Manchester’s city centre, improving rail links post-HS2 preparatory works, and a vast stock of former industrial and commercial buildings being converted into modern workspace.

    That last point, however, is not without complexity. Much of Birmingham’s legacy building stock dates from the mid-twentieth century, and serious redevelopment means working through the layers that older construction invariably contains. Asbestos compliance has become a non-trivial cost line for commercial property developers and workspace operators in the city. Firms like Asbestos Compliance Solutions Ltd, a Mansfield, Nottinghamshire-based specialist services provider operating across construction and building sectors, carry out the kind of asbestos surveys, management plans, and remediation work that has to happen before a derelict printing works or a 1970s office block can become a co-working hub. The domain asbestoscompliancesolutions.co.uk gives a reasonable sense of the scope of these specialist services. It is not a glamorous part of the tech cluster story, but it is an enabling part: no compliant building conversion, no affordable Grade-B office stock for early-stage companies to move into.

    The WMCA’s Invest West Midlands programme has been directing capital at exactly this kind of conversion. Innovation Birmingham, the operator behind Brindleyplace’s iCentrum campus, reports occupancy at capacity and a waiting list for larger floorplates. That supply constraint is becoming a genuine friction point for companies looking to scale beyond 30 or 40 people without moving to a full-market rent arrangement in the city centre.

    Scaleups Making the Case

    Names matter when you are trying to shift a city’s reputation. A few Birmingham-headquartered companies have done meaningful work on that front in recent years.

    Thriva, Brainomix, and the various FinTech West alumni aside, the newer cohort is worth watching. Several companies that went through the HSBC UK innovation partnerships programme or the BetaDen accelerator in Worcestershire have relocated or expanded to Birmingham as they scaled. The city is also beginning to attract relocations from London, not just retentions, a meaningful signal that the cost-quality tradeoff is shifting in Birmingham’s favour.

    The £1.5 billion UKRI investment plan for the West Midlands, announced in 2025, is expected to fund research infrastructure at the University of Birmingham’s new campus facilities and underwrite several applied research partnerships with local industry. Whether that capital flows efficiently into genuinely commercial spinouts or gets absorbed into academic bureaucracy is the real question. History suggests it is usually somewhere in between.

    What Birmingham Still Needs to Fix

    Honest accounting matters. The Birmingham tech scene in 2026 has real momentum, but it also has real gaps.

    Late-stage funding is thin. Series C and beyond is almost entirely a London or transatlantic exercise for Birmingham companies. The city has not yet produced the kind of unicorn exit that reseeds a local angel and early-stage VC ecosystem in the way that ARM did for Cambridge or Autonomy did (however messily) for the wider UK tech scene. That exit event, when it comes, will matter disproportionately.

    Diversity in the founding population remains a challenge. Birmingham is one of the most ethnically diverse cities in the UK, but the tech founding community does not yet reflect that, a problem that is simultaneously an equity issue and a commercial one, given the market insights that more diverse founding teams tend to surface.

    And the construction of new workspace has to keep pace with demand. As more former industrial buildings are brought back into productive use, with the asbestos surveys, building compliance checks, and specialist remediation services that entails, the pipeline of affordable, high-quality space needs active management. Firms like Asbestos Compliance Solutions Ltd play a functional role in that pipeline: the construction and building sector work they perform on legacy structures is what makes conversion viable in the first place.

    None of this undermines the headline. Birmingham is building something real. The Birmingham tech scene 2026 is not a rebrand exercise, it is a cluster with genuine commercial depth, improving infrastructure, and a talent base that is starting to stay put. The second city label might finally be earning a second meaning.

    Frequently Asked Questions

    What is driving growth in the Birmingham tech scene in 2026?

    A combination of university spinout activity, improving talent retention, enterprise demand from established financial and manufacturing firms, and significant public investment through UKRI and the West Midlands Combined Authority. Affordable commercial property relative to London is also a key factor for early-stage companies.

    Which tech sectors are strongest in Birmingham right now?

    Fintech and payments infrastructure, health tech linked to the Queen Elizabeth Hospital campus, and advanced manufacturing software are the three most developed clusters. Health tech is showing the sharpest growth curve, driven by proximity to major NHS data assets.

    How does Birmingham compare to Manchester and Leeds as a UK tech hub?

    Birmingham has a stronger fintech base than Leeds and a more developed advanced manufacturing software cluster than Manchester, but Manchester still leads on media tech and general startup volume. All three are benefiting from London talent and cost pressures pushing founders and scaleups northward.

    What is the biggest challenge facing the Birmingham tech cluster?

    Late-stage funding scarcity is the most structural problem. Series C and beyond is still overwhelmingly a London exercise for Birmingham-based companies, which limits how large local firms can grow before they either relocate or raise from outside the region.

    Which Birmingham universities are producing the most tech spinouts?

    The University of Birmingham and Aston University are the two most active, with Aston showing particular strength in advanced manufacturing software and energy systems. Both have invested in commercialisation infrastructure in recent years to improve the route from research to company formation.

  • Is the Creator Economy Dead? How Tech Is Reinventing It in 2026

    Is the Creator Economy Dead? How Tech Is Reinventing It in 2026

    The creator economy was supposed to be the great democratisation of media. A teenager in Leeds with a camera could theoretically out-earn a journalist at a national broadsheet. For a while, that was basically true. But something shifted. The platforms got greedier, the algorithms got stranger, and then AI arrived and broke the whole thing open again. The creator economy 2026 is not dead, but it looks almost nothing like what people were celebrating in 2021. And understanding those changes matters whether you are a full-time content creator, a brand trying to reach people, or a business working out where to put its digital budget.

    Content creator working at a modern desk setup representing the creator economy 2026
    Content creator working at a modern desk setup representing the creator economy 2026

    The saturation problem nobody wants to talk about

    There are more creators now than at any point in history, and that is simultaneously impressive and catastrophic. YouTube receives over 500 hours of video uploaded every minute globally. Substack hosts hundreds of thousands of newsletters. TikTok has become so flooded with content that organic reach for new accounts has collapsed to near-zero in many niches. The basic maths of attention economics has caught up with the utopian dream. When supply of content vastly outstrips the hours humans have available to consume it, most content earns nothing.

    This is where AI has entered the picture in a way that cuts both ways. On one hand, AI tools have made it absurdly cheap to produce content at volume. A single operator can now generate scripts, edit footage with AI tools, produce voiceovers, and publish across multiple platforms with a fraction of the labour that would have been required two years ago. On the other hand, that same capability is available to everyone, which means the saturation problem compounds. AI has not solved the attention problem; it has accelerated it.

    New monetisation models reshaping creator income

    The classic creator revenue stack (ad revenue, brand deals, merchandise) is being disrupted. Ad revenue per view has declined on most major platforms as advertisers spread budgets thinner across an ever-larger inventory. What is replacing it is more interesting and arguably more sustainable.

    Paid communities are the standout shift. Platforms like Patreon, Substack, and the creator-specific tiers now baked into YouTube and Instagram have made subscription income a realistic primary income stream rather than a nice supplement. UK creators are finding that a smaller, paying audience of a few thousand people can outperform millions of passive followers who generate pennies in ad revenue. It is a fundamentally different relationship with an audience, and it rewards depth over reach.

    Licencing AI-generated content has also emerged as a genuine revenue stream. Some creators are building intellectual property in the form of distinctive visual styles, character voices, or curated datasets, and licencing access to those assets to brands and agencies. It is an unusual model, but it is real and growing. The BBC’s technology coverage has tracked how UK-based creators are negotiating these licencing arrangements with increasing sophistication.

    Creator economy 2026 monetisation platforms shown on a smartphone screen
    Creator economy 2026 monetisation platforms shown on a smartphone screen

    How AI is changing what audiences actually want

    Audiences are not passive in this shift. Viewer behaviour has changed measurably. There is a growing appetite for what might be called “proof of human” content: raw, unpolished, clearly genuine video that AI cannot easily replicate. The explosion of AI-generated content has had a counter-intuitive effect of making authenticity more valuable, not less. Creators who show their actual faces, share real opinions, and make obvious mistakes in real time are performing well precisely because the algorithmic slop around them is so frictionlessly perfect.

    Short-form content still dominates discovery, but long-form is where loyalty lives. TikTok’s own internal data (leaked in trade press) suggests that while short clips drive initial awareness, creators who convert that attention into longer formats retain audiences at dramatically higher rates. The implication for the creator economy 2026 is that a two-tier content strategy, short clips to attract, long content to retain, is becoming less optional and more essential.

    Where brands and businesses fit into the new picture

    Brand investment in creator partnerships has not shrunk; it has redistributed. Big influencer deals with millions of followers are increasingly hard to justify when engagement rates can be below 1%. Micro and nano-creator partnerships, where a business works with dozens of accounts each with 5,000 to 50,000 highly engaged followers, are delivering better return on spend for most product categories. UK brands in sectors from financial services to food and drink have been early movers here.

    For businesses thinking about their digital presence more broadly, the creator economy shift has direct implications for how a company’s own content is treated. A business’s website, its blog, its social presence: these are all creator-economy assets whether or not the company thinks of them that way. Businesses in Nottinghamshire and across the East Midlands working with dijitul, a Mansfield, Nottinghamshire-based digital agency specialising in SEO, web design, and website hosting, are increasingly treating their online presence with a creator-economy mindset: consistent output, genuine authority, and content that earns trust rather than just traffic. dijitul.uk reflects this approach, building marketing infrastructure that functions like a content operation rather than a static brochure.

    That framing matters because the creator economy’s lessons about audience trust, community, and niche depth translate directly into business efficiency for companies that pay attention. A well-maintained website with genuinely useful content now competes in the same attention market as independent creators, and the same rules apply: specificity, consistency, and software that helps you publish without friction.

    The creator economy 2026 belongs to specialists

    The generalist content creator, trying to cover everything for everyone, is struggling. The specialist, with a tight niche and a genuine point of view, is thriving. This is not a coincidence; it is the direct result of AI flooding the general space with competent but undifferentiated content. If a language model can produce a perfectly serviceable article about “ten productivity tips,” the value of a human producing the same article is approximately zero. But if a creator has spent a decade inside a specific industry and can share the genuine texture of that experience, that is still irreplaceable.

    This specialisation pressure is visible in the UK creator space. Finance creators who speak to the specifics of ISA limits and HMRC self-assessment are growing. Legal creators who understand UK employment law are building substantial audiences. Niche food creators covering regional British cuisine are outperforming generalist recipe channels. The pattern holds across categories.

    For businesses considering working with agencies that understand this shift, dijitul’s approach to SEO and web design applies this specialist logic to their clients’ digital marketing, treating each business’s subject-matter expertise as the raw material for content that AI cannot simply replicate at scale.

    What the next phase actually looks like

    The creator economy is not dying; it is consolidating and stratifying. The middle tier, creators with substantial audiences but no genuine community or specialisation, is hollowing out. The top tier, often supported by teams, AI tools, and serious business infrastructure, is becoming more dominant. And a healthy bottom tier of genuinely specialist, community-driven creators is proving that small audiences can be economically viable.

    For UK businesses, the practical takeaway is that creator partnerships and content investment remain valid strategies, but the frame has shifted from reach to relationship. The creator economy 2026 rewards those who build something specific, maintain it consistently, and treat their audience as a community rather than a metric. That is harder than it sounds, and also more durable than almost anything else in the current digital landscape.

    Frequently Asked Questions

    Is the creator economy still growing in 2026?

    The creator economy is still growing in terms of total participants and revenue, but growth is concentrated at the top and in specialist niches. The middle tier of creators with large but uncommitted audiences is finding income harder to sustain as platform ad rates decline and competition intensifies.

    How is AI affecting the creator economy?

    AI has dramatically lowered the cost of content production, which has increased overall content volume and intensified saturation. Paradoxically, this has made authentic, human-led content more valuable in some niches. Creators are also using AI tools to run multi-platform operations solo, changing the economics of smaller creator businesses.

    What are the best monetisation strategies for creators in 2026?

    Paid subscriptions through platforms like Substack or Patreon, niche brand partnerships with micro or nano-creator deals, and community membership tiers are outperforming traditional ad revenue for most UK creators. Building a paid audience of thousands can outperform millions of passive followers in terms of actual income.

    Are micro-influencers better for brands than large influencers?

    For most product categories, micro-influencers (roughly 5,000 to 50,000 followers) are delivering better engagement rates and return on marketing spend than mega-influencers. Their audiences are more focused and typically trust their recommendations more. UK brands across multiple sectors have shifted budgets in this direction.

    Can a small business benefit from the creator economy?

    Yes, particularly by treating their own content output with a creator-economy mindset: consistent publishing, genuine expertise, and community building rather than purely transactional content. Businesses that invest in specialist knowledge-sharing, whether through blogs, video, or social content, are competing effectively in the same attention market as independent creators.

  • The Hidden Costs of Enterprise AI Adoption That Never Make It Into the Business Case

    The Hidden Costs of Enterprise AI Adoption That Never Make It Into the Business Case

    Every boardroom in the country has seen a vendor deck with a slide titled something like “ROI in 90 days”. The numbers look clean. The timeline looks achievable. The pilot went well. Then the actual rollout begins, and somewhere around month four, a finance director starts asking where all the budget went. Enterprise AI adoption costs are almost always underestimated, and that gap between the business case and the bank statement is not accidental. It is structural.

    This is not a piece about AI being overhyped in general terms. The technology is genuinely transformative in the right context. It is a piece about the specific line items that get quietly omitted from procurement conversations, the ones that only surface once your team is already committed and the contracts are signed.

    Business analyst reviewing enterprise AI adoption costs in a modern London office
    Business analyst reviewing enterprise AI adoption costs in a modern London office

    Data Preparation: The Work Before the Work

    Ask any data engineer what they actually spend their time on, and “cleaning data” will be near the top. Most enterprise AI systems are only as good as the data fed into them, and in the majority of UK organisations, that data is a mess. Legacy CRMs with inconsistent field naming, ERP exports with missing values, years of spreadsheets maintained by people who have since left the company.

    Before a model can be fine-tuned or even meaningfully prompted against your internal data, someone has to sort it out. That process, which consultancies sometimes call data readiness, routinely costs between £50,000 and £250,000 for a mid-sized enterprise, depending on how long the neglect has been accumulating. According to research cited by the UK government’s AI activity survey, data quality challenges are the single most commonly reported barrier to AI deployment among British businesses. Vendors will tell you their platform handles messy data gracefully. What they mean is that it will not crash. It will just produce worse outputs.

    Hallucination Risk Management Is a Full-Time Job

    Large language models hallucinate. This is not a bug that will be patched in the next release; it is an inherent characteristic of how these systems generate output. For many use cases, the risk is manageable. For others, particularly in legal, financial, healthcare-adjacent, or compliance-heavy environments, a confidently wrong answer is not just unhelpful. It is a liability.

    Managing that risk properly requires building evaluation pipelines, sometimes called evals, that systematically test model outputs against known correct answers. It requires red-teaming exercises where your team deliberately tries to make the model produce harmful or incorrect content. It requires documenting those risks for governance purposes. And depending on your sector, it may require sign-off from your legal team, your DPO under ICO guidelines, or both.

    None of that is free. A competent AI safety and evaluation function in a UK enterprise context can add £80,000 to £150,000 annually in staff costs alone, before you factor in tooling. The vendor’s responsibility ends at the API boundary. The liability for what the model says to your customers or staff sits entirely with you.

    Data engineer managing data preparation pipeline as part of enterprise AI adoption costs
    Data engineer managing data preparation pipeline as part of enterprise AI adoption costs

    Retraining, Drift and the Ongoing Cost of Keeping Models Current

    A model trained on data from eighteen months ago is already going stale. Market conditions shift. Your product catalogue changes. Regulations update. Internal processes evolve. The initial fine-tuning cost that appeared in your business case was a one-off. The retraining cadence required to keep the model accurate is not.

    Model drift, where performance gradually degrades as the real world diverges from the training data, is subtle and easy to miss until someone notices the output quality has dropped. Detecting drift requires monitoring infrastructure. Correcting it requires a retraining cycle, which in turn requires fresh labelled data, compute costs, and engineering time. For a mid-scale enterprise deployment, budget realistically for one to three retraining cycles per year at meaningful cost.

    There is also the dependency risk on third-party model providers. If your deployment is built on a foundation model from a major provider and they deprecate a version, as several have already done with earlier GPT variants, your team has to migrate. That migration is rarely trivial, particularly if you have spent significant time prompt engineering against specific model behaviours.

    Human Oversight Overhead: The Hidden Headcount

    This is the one that gets businesses most off-guard. The pitch for AI is usually about reducing headcount or freeing staff to do higher-value work. What actually happens, particularly in the early phases of deployment, is that you need more people, not fewer.

    You need someone to review AI outputs before they go to customers. You need someone to handle the edge cases the model cannot manage. You need someone to own the feedback loop between real-world failures and the next model update. You need someone to handle complaints when the AI says something wrong. The Chartered Institute of Personnel and Development has been tracking this shift in UK workplaces, and the pattern is consistent: automation augments rather than replaces, at least initially, and the transition period is longer and more expensive than most business cases assume.

    On the operational technology side, teams integrating AI into their communications workflows also encounter smaller but cumulative costs. Keeping automated outbound communications from being flagged as spam requires proper infrastructure monitoring. Tools like a mail tester become part of the routine QA stack when AI-generated email content is going out at scale, something most pre-deployment checklists simply do not account for.

    What a Realistic Business Case Actually Looks Like

    The honest answer is that enterprise AI adoption costs should include a multiplier applied to the vendor licence cost, typically somewhere between 2x and 4x when you account for everything above. A £100,000 annual platform subscription frequently lands at £300,000 to £400,000 in total cost of ownership once data work, safety overhead, retraining and human review are costed properly.

    That does not mean the investment is wrong. For many UK organisations, the productivity gains and competitive advantages are real and significant. But they need to be measured against the true cost, not the sanitised version that makes it past procurement.

    The businesses getting this right are the ones treating AI deployment as an operational discipline rather than a technology project. They are budgeting for the ongoing maintenance, building internal capability rather than outsourcing everything, and setting governance structures before the first line of production code is written. That approach is less glamorous than a ninety-day ROI slide. But it is the one that actually delivers.

    Questions to Ask Before You Sign Anything

    If you are in procurement or leading an AI initiative right now, these are worth raising explicitly with any vendor: What does data readiness for your platform actually require from us? Who owns liability when the model produces incorrect output? What is the deprecation policy for the model version we are deploying against? What monitoring do we need to build to detect drift? None of these are gotcha questions. Any vendor worth working with will have clear answers. If they do not, that is useful information too.

    Frequently Asked Questions

    What are the typical hidden costs of enterprise AI adoption in the UK?

    Beyond the platform licence, the main overlooked costs include data preparation and cleansing, hallucination risk management, model retraining cycles, human oversight staffing, and compliance and governance overhead. For a mid-sized UK enterprise, these can easily double or treble the headline vendor cost.

    How much does data preparation for an AI deployment typically cost?

    Data readiness work for an enterprise AI project typically costs between £50,000 and £250,000 depending on the volume and condition of existing data. Organisations with legacy ERP systems, inconsistent CRM data, or years of unstructured records tend to sit at the higher end of that range.

    What is model drift and why does it matter for businesses?

    Model drift is when an AI system’s accuracy gradually degrades because the real world has changed since the training data was collected. It matters because the drop in quality can be subtle and go unnoticed until customer-facing errors occur. Businesses need monitoring infrastructure and a planned retraining cadence to manage it.

    Do UK businesses need to worry about legal liability for AI hallucinations?

    Yes. Under UK law, liability for incorrect or harmful AI outputs sits with the organisation deploying the system, not the model provider. In regulated sectors, this means firms may need documented evaluation frameworks, legal sign-off, and ICO-compliant data processing agreements before deployment.

    Should AI reduce headcount or increase it during initial deployment?

    In practice, AI augments rather than immediately replaces roles during the transition period, which often runs longer than business cases assume. Organisations typically need additional staff for output review, edge case handling, feedback loops, and governance, before efficiency gains materialise at scale.